Smart Money Pulse - '26 W39
The Crowded Bond Bet Moved Into the Part of the Market Your Bond Fund Owns
For weeks the tension in Treasuries sat at the edges of the maturity range, in the 2-Year and the 10-Year. This week it moved to the middle. Dealers in the 5-Year Treasury dropped two full tiers to the bottom of their two-year range (z=-2.10), the only new extreme reading anywhere on the board, while the hedge fund crowd on the other side sits near the very top of its own range.
That matters more than it sounds for an ordinary portfolio. The five-to-ten-year stretch of maturities is the core of most broad bond funds, BND and AGG included, so this is not some trader’s corner of the market; it is the middle of the bond sleeve in a typical 60/40 or target-date account. Both big groups are still short the contract outright, so the story is where each one sits against its own history, not a bet on which way yields go.
This is Tuesday’s picture, and the days since have been rough for bonds. Treasuries sold off as markets began pricing in another Fed rate hike in October, with the damage steepest at the longest maturities, the dollar at an eight-week high and the S&P 500 and Nasdaq each off about half a percent. None of that shows anyone changing their position; PCE (the Fed’s preferred inflation measure) was on today’s calendar, and next week’s report is the first that can show how the pros handled the selloff.
This Week’s Positioning
The 5-Year Treasury: the pressure concentrated instead of fading
Last week the dealer extremes sat in the 2-Year and the 10-Year; both eased a notch this week while the 5-Year took their place. The hedge fund crowd is simultaneously near the top of its range in the 2-Year, the 5-Year and the 30-Year, and in the 5-Year and 30-Year it is still actively adding. That is a lot of like-minded money parked across the maturities a core bond fund holds, which describes a fragile arrangement, not a direction.
Watch: the September jobs report on October 2 (the monthly payrolls count, the next big number for interest rates). It lands squarely on these books, and on BND or AGG in your account.
The 10-Year Treasury: dealers let go of the floor, and did it in a hurry
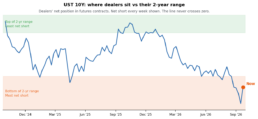
Dealers climbed off the bottom of their range to a reading that is still stretched but no longer extreme (z=-1.79), and the size of that shift was far outside what the week after a quarterly options expiration normally produces. Small traders, the group your own account belongs to, went the other way: they are leaning harder short on the 10-Year than at almost any point in the past two years. A small-trader crowd that lopsided has often been where the crowd gets it wrong, though that is a habit worth watching, not a forecast.
Watch: next week’s report, built from the September 29 snapshot. It is the first to capture the post-Tuesday bond selloff, and it will show whether dealers slid back toward the floor or held their distance.
Large-cap stocks: dealers covered, and the book landed near balance
S&P 500 dealers covered enough to move from neutral into a mildly above-average reading (z=+0.82), though they are still short outright, just less short than usual, while Nasdaq dealers slid back to the middle of their range. The hedge fund crowd stepped back to neutral in both, so the tug-of-war that had been building in tech unwound before it stretched. For an SPY or QQQ holder, the positioning under your core stock funds is unremarkable this week.
Watch: whether the S&P 500 holds the 7,800 area through the jobs report, after giving back about half a percent since Tuesday.
The Swiss franc: the fast money and the dealers squared off
Dealers stepped up into the stretched part of their range with a genuine long on the franc, while the hedge fund crowd is short it from near the bottom of its own range (z=-1.74), so the two now sit in opposite corners. Put plainly, the speculative money is betting the franc weakens against the dollar, and small traders are leaning the same way. For a regular investor this shows up through the dollar, which firmed since Tuesday and tends to weigh on unhedged international funds.
Watch: the franc near $1.22, where it sits after slipping almost one percent since Tuesday.
Elsewhere, the rest of the board is background. Short-term rate futures remain the one contract where both professional groups are stretched in opposite directions, though dealers trimmed a large slice there this week; small caps still carry the most one-sided speculative short among the stock indexes and were the weakest index since Tuesday, down almost two percent; institutions remain unusually heavy sellers of volatility protection with the fear gauge near 14.8; the Japanese yen and Australian dollar dealer books drifted back to neutral after big weekly swings; the euro and British pound dealer books shuffled without landing anywhere new, though the pound’s speculative crowd edged into the stretched low end of its range; Bitcoin’s speculative crowd eased back a tier while the dealer long stays thin; copper’s physical hedgers and speculative crowd are back at opposite ends of their ranges; gold, silver and crude show nothing at a genuine extreme; and in natural gas only the swap dealer book sits at the top of its range, where it also sat last week.
Know Where You Stand
- Look up the duration figure on your core bond fund this weekend. Duration is on every fund’s fact sheet and roughly tells you how much the fund moves when rates move; broad funds like BND and AGG sit around six years, right in the stretch of maturities where the professional books are most crowded, while a short fund like SHY sits near two and a long fund like TLT well past fifteen.
- Stocks and bonds fell together this week, so look at how your balanced mix actually behaved. If you hold a 60/40 or target-date fund, pull up the change since Tuesday on the stock and bond sides separately (SPY and BND are fine stand-ins); knowing that your bonds can drop alongside your stocks when rates are the story is the useful part, and it is not by itself a reason to rebalance.
- If you own copper or a mining fund, know that the speculative crowd there is packed near the top of its range. Managed money in copper sits near the top of its two-year range against physical hedgers near the bottom of theirs, which describes who owns the trade rather than where the price goes; if CPER or a miner fund like COPX has grown into a meaningful slice of your account, size it on purpose.
Data: CFTC COT Report 2026-09-22 | Prices as of 2026-09-25 | 104-week lookback
Liquidity Trajectory '26 W39
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-09-22 | Generated: 2026-09-25 15:44 ET
EXECUTIVE SUMMARY
- Rates stress rotated into the belly of the curve. UST 5Y dealers stepped two tiers from MODERATE to EXTREME SHORT (z -1.45 to -2.10, the 1.0th percentile, WoW -77,974), the only new dealer extreme on the board, against leveraged funds held at the 99.0th percentile of their range (lev z +2.27, adding ~111,324/wk). The 5Y extreme carries options corroboration (OptZ=-1.21) and a measured realized vol of 1.19x the all-week average for that regime (n=54). The wings moved the other way: UST 10Y dealers released EXTREME to ELEVATED on the board’s largest event deviation (event z +4.70^, WoW +138,734), and UST 2Y slipped from EXTREME to ELEVATED.
- The leveraged duration crowd extended at the long end while the front end eased. UST 30Y leveraged funds pushed to the 99.0th percentile (lev z +2.45, adding ~48,821/wk) on a thin, concentration-flagged book; like the 5Y and 2Y, they remain net short in absolute contract terms and the z reads their posture versus their own range. SOFR 3M is still the board’s both-sides stretch, but dealers liquidated -372,565 contracts (event z -1.81^) and leveraged funds released a tier to ELEVATED SHORT; the SOFR futures extreme carries an options caveat and a heavy spread share, so read it as a basis footprint.
- Post-OpEx FX flow was outsized across the majors. The yen book posted the largest dealer flow z on the board (+3.30), carrying dealers from MODERATE SHORT back to NEUTRAL; sterling dealers added +39,919 to a genuine long (flow z +2.45); and the franc stepped to ELEVATED LONG against a leveraged short, the one FX book with opposed stretches. Copper Commercials stepped to ELEVATED SHORT against Managed Money at the 99.0th percentile, the commodity board’s only opposed pair.
- Equity dealers covered into both index transitions. S&P 500 dealers moved from NEUTRAL to a MODERATE LONG regime while staying net short -635,484 contracts outright (less short than usual, not long), and Nasdaq dealers released MODERATE SHORT back to NEUTRAL; leveraged funds in both indexes fell back to NEUTRAL. Group equity dealer average is +0.58z. The options-implied dealer delta is stretched short in both indexes, so the futures-side covering is not echoed in the options book.
- Catalyst line: PCE is on today’s calendar (Sep 25) and lands on the SOFR, 2Y and 5Y books that carry the board’s crowding; NFP follows Oct 2, seven days out, on the same front end and the dollar ledger.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-09-22 Tuesday snapshot; the price moves below run through Friday September 25 on a different clock. Price action does not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | -0.46% | ES=F, modest giveback |
| Nasdaq | -0.52% | NQ=F |
| Russell 2000 | -1.88% | RTY=F, the weakest equity index |
| VIX | +4.86% | ^VIX 14.90, still in the mid-14s |
| Bitcoin | -2.59% | BTC-USD |
| Ether | -2.27% | ETH-USD |
| UST 2Y | -0.36% | ZT=F futures down = front-end yields up |
| UST 5Y | -0.74% | ZF=F futures down = yields up |
| UST 10Y | -1.03% | ZN=F futures down = yields up |
| UST 30Y | -2.70% | ZB=F futures down = long-end yields up, the largest rates move |
| Dollar Index | +0.38% | DX-Y.NYB, USD up |
| JPY | +0.61% | 6J=F up = yen up vs dollar |
| GBP | -0.59% | 6B=F down = sterling down vs dollar |
| CHF | -0.91% | 6S=F down = franc down vs dollar |
| Copper | +0.21% | HG=F, flat |
No scheduled macro release landed between the snapshot and publication; PCE is on today’s calendar. The dominant driver was a Treasury selloff on renewed rate-hike pricing: headlines cite a hot inflation reading and Fed commentary pushing markets toward an October hike, a key rate at a 19-year high and the dollar at an 8-week high, with the selloff steepest at the long end. All of this is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund or asset manager repositioning, and the next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 5Y | REGIME STEP TO EXTREME + OPPOSED EXTREMES | -1.45 to -2.10 (Δ -0.65) | +2.08 to +2.27 (Δ +0.19) | dlr MODERATE to EXTREME SHORT; lev EXTREME LONG (held) | dealer net -933,316, flow z -1.77, event z -1.37; lev net -1,858,062, still short outright; AM z -1.42; small traders z -1.43 |
| 2 | UST 10Y | EXTREME RELEASED ON THE BOARD’S LARGEST EVENT FLOW | -2.78 to -1.79 (Δ +0.99) | +0.40 to +0.19 (Δ -0.21) | dlr EXTREME to ELEVATED SHORT; lev NEUTRAL (held) | dealer 2.9th pctl, net -580,674, flow z +3.29; AM long z +1.47 on +2,531,384; Other Reportables z -1.57 and small traders z -1.79, both washed out; RV 1.01x (n=54), no amplification; OptZ=-1.50 corroborates |
| 3 | SOFR 3M | OPPOSED STRETCH, LEV RELEASED A TIER | +2.41 to +2.02 (Δ -0.39) | -2.08 to -1.68 (Δ +0.40) | dlr EXTREME LONG (held); lev EXTREME to ELEVATED SHORT | dealer 92.3rd pctl, outright +3,152,190, flow z -2.03; lev net -2,444,986; AM z -1.85; 38.7% of lev gross in spread structure; OptZ=-4.07 caveat, options book runs the other way; 90L/90S # |
| 4 | UST 2Y | EXTREME RELEASED, OPPOSED STRETCH HELD | -2.04 to -1.86 (Δ +0.18) | +2.37 to +2.12 (Δ -0.25) | dlr EXTREME to ELEVATED SHORT; lev EXTREME LONG (held) | dealer 1.9th pctl, net -523,460, WoW +12,820; lev net -1,350,740, still short outright; AM z -1.40; small traders z -1.75, washed out; RV 1.26x (n=68); OptZ=-0.34 caveat |
| 5 | UST 30Y | LEV CROWD EXTENDED AT THE LONG END | -0.69 to -0.83 (Δ -0.14) | +2.01 to +2.45 (Δ +0.44) | dlr MODERATE SHORT (held); lev EXTREME LONG (held) | lev net -162,052, still short outright, on a thin 41L/37S # book; dealer 22.1st pctl, net -250,961; AM z -1.72; Other Reportables z -2.29; top-4 37.7%; OptZ=-0.09 |
| 6 | CHF | REGIME STEP TO ELEVATED + OPPOSED STRETCH | +1.43 to +1.56 (Δ +0.13) | -1.54 to -1.74 (Δ -0.20) | dlr MODERATE to ELEVATED LONG; lev ELEVATED SHORT (held) | dealer 92.3rd pctl, net +68,285 (genuine long franc), 4 straight weeks of net increase; lev net -16,457 short franc; small traders z -1.60, washed out; top-4 71.8% #; RV 1.25x (n=55); OptZ=+1.52 corroborates |
| 7 | Copper | REGIME STEP TO ELEVATED + OPPOSED STRETCH | -1.21 to -1.73 (Δ -0.52) | +1.02 to +1.73 (Δ +0.71) | Commercials MODERATE to ELEVATED SHORT; Managed Money MODERATE to ELEVATED LONG | Commercials 1.9th pctl, net -112,402 hedge, WoW -14,384, flow z -2.21, event z -1.46; Managed Money net +82,649 long; Swap Dealers z -0.67; Other Reportables z +1.18; 29L/35S #; top-4 30.7% |
| 8 | GBP | OUTSIZED DEALER BUILD, LEV AT RANGE LOW | +0.60 to +1.29 (Δ +0.69) | -1.12 to -1.52 (Δ -0.40) | dlr MODERATE LONG (held); lev MODERATE to ELEVATED SHORT | dealer 91.3rd pctl, net +108,142 (genuine long sterling), event z +2.00^; lev net +13,239, still long outright at the bottom of its range; AM net -115,805 holds the sterling short (z -1.12); OptZ=+2.10, options book stretched long |
| 9 | JPY | REGIME TRANSITION ON OUTSIZED FLOW | -1.00 to -0.43 (Δ +0.57) | +1.63 to +1.20 (Δ -0.43) | dlr MODERATE SHORT to NEUTRAL; lev ELEVATED to MODERATE LONG | WoW +60,286, event z +3.72^; dealer 32.7th pctl, net -108,284 (still short yen); lev net +7,423 long yen; AM z +0.23; top-4 47.7%; OptZ=-0.73 |
| 10 | S&P 500 (Consol) | REGIME TRANSITION, DEALERS COVERING | +0.40 to +0.82 (Δ +0.42) | +0.55 to -0.31 (Δ -0.86) | dlr NEUTRAL to MODERATE LONG; lev MODERATE LONG to NEUTRAL | dealer 76.0th pctl, WoW +46,311, flow z +1.94; lev net -375,616; AM z -0.03; Other Reportables z -1.50; OptZ=-2.04; E-Mini dlr +0.23 to +0.87 (Δ +0.64) |
| 11 | Nasdaq (Consol) | REGIME TRANSITION BACK TO NEUTRAL | -0.62 to -0.12 (Δ +0.50) | +1.00 to +0.07 (Δ -0.93) | dlr MODERATE SHORT to NEUTRAL; lev MODERATE LONG to NEUTRAL | dealer 51.0th pctl, net -54,809, WoW +15,143, flow z +2.23; lev net -35,670; AM z +0.32; OptZ=-2.53; Mini dlr -0.82 to -0.09 (Δ +0.73) |
| 12 | Russell 2000 | LEV SHORT DEEPENED AGAINST A DEALER LONG | +1.11 to +1.02 (Δ -0.09) | -1.52 to -1.85 (Δ -0.33) | dlr MODERATE LONG (held); lev ELEVATED SHORT (held) | dealer 86.5th pctl, genuine outright long +75,744, WoW -4,858; lev net -107,982 short; AM z -0.23; OptZ=+0.28 |
| 13 | EUR | OUTSIZED FLOW, FOURTH STRAIGHT WEEKLY BUILD | +0.70 to +1.00 (Δ +0.30) | -1.01 to -0.94 (Δ +0.07) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -220,952 (short euro, high end of its short range, not a long), 77.9th pctl, WoW +37,128, flow z +2.02, event z +1.90^; lev net -26,694 short euro; AM +216,483 holds the euro long; OptZ=+0.48 |
| 14 | AUD | REGIME TRANSITION TO NEUTRAL | -0.58 to -0.42 (Δ +0.16) | +1.58 to +1.47 (Δ -0.11) | dlr MODERATE SHORT to NEUTRAL; lev ELEVATED to MODERATE LONG | dealer net -28,008 (short AUD), WoW +10,295; lev net +58,726 long AUD; AM z -0.89; top-4 71.5%; OptZ=+0.61 |
| 15 | Ether | OUTSIZED FLOW, DEALER LONG BUILT | +0.53 to +0.98 (Δ +0.45) | +0.34 to -0.26 (Δ -0.60) | dlr MODERATE LONG (held); lev NEUTRAL (held) | dealer 85.6th pctl, net +12,372 (structural long), WoW +1,801, flow z +1.51, event z +2.84^; lev net -10,617; AM z -1.22; top-4 78.0% |
| 16 | MXN | LEV CROWDED LONG RELEASED A TIER | -1.06 to -0.63 (Δ +0.43) | +2.06 to +1.66 (Δ -0.40) | dlr MODERATE SHORT (held); lev EXTREME to ELEVATED LONG | dealer net -74,696 (short peso), WoW +19,070, flow z +1.48; lev net +79,188 long peso; AM z +0.25; top-4 78.0%; OptZ=+0.60 |
| 17 | VIX | PROTECTION DEMAND LOW, AM VOL SELLING AT AN EXTREME | +0.91 to +1.04 (Δ +0.13) | +0.76 to +0.82 (Δ +0.06) | dlr MODERATE LONG (held); lev MODERATE LONG (held) | dealer 87.5th pctl, net +66,943 long VIX = low protection demand; AM net short vol at z -2.35, the board’s most negative AM reading; lev net -15,015; 29.4% of lev gross in spread structure; OptZ=+0.00 |
| 18 | Bitcoin | LEV RELEASED A TIER, DEALER STRUCTURAL LONG LOW | -0.93 to -0.91 (Δ +0.02) | +1.61 to +1.25 (Δ -0.36) | dlr MODERATE SHORT (held); lev ELEVATED to MODERATE LONG | dealer 14.4th pctl, net +3,647 (structural long near its range low); lev net -7,953, short outright; AM z -1.62; top-4 57.5%; OptZ=-0.47 |
| 19 | Natural Gas | SWAP DEALER EXTREME, REST QUIET | +0.22 to -0.06 (Δ -0.28) | -0.89 to -0.28 (Δ +0.61) | Commercials NEUTRAL (held); Managed Money MODERATE SHORT to NEUTRAL | Swap Dealers z +2.29 on +225,714; Commercials net -23,627; Managed Money net -65,632 short; Other Reportables z -1.42 |
| 20 | USD Index | QUIET, AM HOLDS THE DOLLAR LONG | -0.99 to -1.00 (Δ -0.01) | -0.15 to -0.10 (Δ +0.05) | dlr MODERATE SHORT (held); lev NEUTRAL (held) | dealer 20.2nd pctl, net -15,538 (short DXY); AM +16,772 holds the DXY long (z +1.10); small traders z +1.13; top-4 72.9% on a 6L/0S ledger; OptZ=+0.00 |
| 21 | CAD | QUIET, SIGN DISCIPLINE | -0.92 to -0.72 (Δ +0.20) | +0.97 to +0.59 (Δ -0.38) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer net +63,812 (still a genuine long CAD), WoW +15,198; lev net -46,861 short CAD; AM z +0.71; top-4 57.1% |
| 22 | WTI Crude | MANAGED MONEY STEPPED UP A TIER | +0.71 to +0.83 (Δ +0.12) | +0.32 to +0.94 (Δ +0.62) | Commercials MODERATE LONG (held); Managed Money (lev) NEUTRAL to MODERATE LONG | WTI Commercials 83.7th pctl, net +315,753 (unusually net long for this cohort); Managed Money net +142,588; Swap Dealers z -1.71; top-4 6.7%, the least concentrated on the board |
| 23 | Gold | HEDGERS HIGH, SPECULATORS FLAT | +1.01 to +1.06 (Δ +0.05) | -0.01 to -0.15 (Δ -0.14) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 73.1st pctl, net -24,872 hedge; Managed Money net +131,334 long; Swap Dealers z -1.04; Other Reportables hold 39.6% of OI, the largest mid-size share on the board |
| 24 | Silver | QUIET | +1.06 to +0.91 (Δ -0.15) | -0.93 to -0.86 (Δ +0.07) | Commercials MODERATE LONG (held); Managed Money MODERATE SHORT (held) | Commercials 70.2nd pctl, net -18,512 hedge; Managed Money net +13,309 still long outright; Swap Dealers z +0.75; small traders 26.0% of OI, the largest small-trader share on the board |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
Read as one curve, the stress moved rather than eased. Last week the dealer extremes sat in the 2Y and the 10Y; this week both released a tier while the 5Y dropped into the only new extreme on the board, so the dealer short now concentrates in the belly. The 10Y release came on repositioning far outside what the post-OpEx phase normally produces, which marks it as the week’s most unusual book even as its level eased. The front end relaxed on both sides: SOFR dealers liquidated a large slice of their long and the leveraged short released a tier, leaving the pair still opposed but less stretched.
The leveraged cohort tells the other half. Leveraged funds sit at the top of their own range in the 2Y, 5Y and 30Y at once, and the 30Y crowd is the one still actively building, on a thin book. All of these remain short in absolute contract terms, so the z describes posture versus history rather than an outright long. In the 5Y, dealers and leveraged funds are opposed at full stretch, the configuration that would imply squeeze fuel if either side is forced to move; that is market structure, not a directional call. Asset managers hold the duration long near the top of their range only in the 10Y and sit at the low end of theirs from SOFR through the 30Y, and small traders are washed out across the note complex, context only.
Caveats carry over and apply across the curve. The options-implied dealer delta corroborates the 5Y and 10Y futures readings, the only places the options-hedging hypothesis has support this week; it does not support the 2Y or SOFR, which read as basis or directional footprints, and SOFR’s spread share means its directional read overstates conviction. Measured realized vol is modestly elevated for the 2Y and 5Y regimes and flat for the 10Y, so the short-gamma vol amplification inference stays a hypothesis.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
The week’s FX story is size of flow, not a single dollar view. Dealers covered hard across the majors in the post-OpEx week, and three books cleared the gate on flow alone. The yen dealer book reset to neutral for the third straight week of violent turnover, with dealers still short yen outright and leveraged funds long; the two sides remain opposed in sign but neither is stretched. Sterling carries the sharpest sign trap on the board: the leveraged regime reads ELEVATED SHORT while leveraged funds are actually net long sterling outright, alongside dealers who hold a genuine long, so the two are on the same side and asset managers hold the sterling short. The options book is stretched long with the dealer futures there. In the euro, dealers built for a fourth straight week but remain short the contract at the high end of their short range, the same side as leveraged funds, with the euro long sitting with asset managers.
The franc is the FX book where level and counterparty structure line up: dealers hold a genuine long in the upper part of their range against a leveraged short near the bottom of its range, with the options-implied dealer delta stretched the same way and a measured realized vol above average for that regime. The Aussie crossed back to neutral on the dealer side and the peso’s leveraged crowd released a tier, though both still hold a leveraged long against a dealer short.
Cross-checked against the Dollar Index, the buy-side still does not tell one coherent dollar story. Asset managers hold the DXY long high in their range while also holding the euro long outright and the sterling and franc shorts, and leveraged funds sit neutral on the index. That split is worth a second look rather than a headline.
Two FX books carry analog data. The franc’s five prior ELEVATED LONG DELTA episodes (2026-06-23, 2025-04-01, 2025-02-25, 2024-12-24, 2024-12-10) returned a median -0.79% over four weeks, 2 of 5 bullish, against an unconditional base rate of +0.04% median and 51% bullish across all 885 weeks. Sterling’s five prior MODERATE LONG DELTA episodes returned a median +0.33%, 3 of 4 resolved bullish, against a base rate of +0.03% median and 51% bullish. Neither deviates meaningfully from its base rate on so few episodes; historical context, not a signal, and the windows are anchored to Tuesday, so three sessions have already elapsed.
Equities (S&P 500, Nasdaq, Russell 2000)
Both index transitions came from dealer covering rather than a new stretch. S&P 500 dealers crossed into the MODERATE LONG regime on a growing four-week covering trend, but they remain short the contract in absolute terms; the regime word describes being less short than usual. Nasdaq dealers released their moderate short back to the mean on flow the tool flags as large for the event phase. Leveraged funds did the opposite in both, stepping back to neutral, so the cross-cohort tension that built in Nasdaq last week unwound before it stretched. The options-implied dealer delta is stretched short in both indexes, a divergence from the futures-side covering worth noting as context, since the futures book alone is not the full dealer picture. Other Reportables in the S&P 500 sit near the bottom of their range, a mid-size cohort short against the covering.
Russell 2000 remains the one-sided equity book: dealers hold a genuine outright long high in their range while the leveraged short deepened toward the bottom of its own, a crowded-short configuration that would imply squeeze fuel if the short is forced to cover. The tool reads the dealer trend as declining against that, so the counterparty tension is standing rather than building.
VIX, one line: dealers long VIX signals low protection demand, and asset managers sit at an extreme short in vol, the board’s deepest asset manager stretch, with no change in character from last week.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Copper is the only commodity that cleared the gate, and it tightened after last week’s release. Commercials stepped back into an elevated hedge near the bottom of their range while Managed Money climbed a tier to the top of its range, restoring the canonical hedger-versus-speculator opposition at full stretch on a concentration-flagged hedger book. Positioning state only. Copper carries analog data: five prior ELEVATED SHORT DELTA episodes returned a median -2.21% over four weeks, 1 of 4 resolved bullish, against an unconditional base rate of +0.8% median and 55% bullish across 885 weeks. Four resolved episodes are historical context, not a signal.
In WTI crude, Managed Money stepped up a tier while WTI Commercials held an unusually net long posture for a hedger book. Separately, the natural gas Swap Dealer book stays pinned at the top of its range, a standing oddity. Gold and silver sat quiet, hedgers moderately high versus their own ranges and speculators flat to modestly short.
Crypto (Bitcoin, Ether)
The intra-crypto split widened again. Ether dealers built their structural long on flow unusually large for the event phase, while the Bitcoin dealer long stays near the low end of its range and the leveraged cohort there released a tier. Standing caveat, unchanged: crypto dealers are structurally net long, so Bitcoin’s negative z means a thin long rather than an outright short, and leveraged funds in both names remain net short outright despite the Bitcoin regime label. The tool reads this as a crypto-specific divergence rather than a broad risk-off signal, since equity positioning shows nothing comparable.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (Consol) | 6,644.84 – 6,843.86 | 7,795.25 | above zone | 7,199.73 – 7,405.85 | above zone |
| Nasdaq (Consol) | 28,986.82 – 29,924.14 | 30,865.50 | above zone | 29,345.13 – 30,486.67 | above zone |
| Russell 2000 | 2,825.62 – 2,924.76 | 2,860.00 | inside zone | 2,851.67 – 2,949.17 | inside zone |
| VIX | 15.49 – 18.89 | 14.91 | below zone | 14.30 – 16.03 | inside zone |
| Bitcoin | 76,619.80 – 83,215.46 | 83,949.30 | just above zone | 74,231.07 – 80,627.32 | above zone |
| Ether | 2,324.53 – 2,559.01 | 2,690.75 | above zone | 2,322.35 – 2,530.30 | above zone |
| USD Index | 99.51 – 100.95 | 100.98 | at the top edge | – | – |
| CHF | 1.23 – 1.25 | 1.22 | below zone | 1.24 – 1.25 | below zone |
| Gold | 4,168.40 – 4,382.55 | 4,324.00 | inside zone | 3,967.90 – 4,181.31 | above zone |
| Silver | 57.96 – 63.93 | 64.79 | above zone | 64.98 – 72.04 | just below zone |
| Copper | 5.83 – 6.08 | 6.77 | above zone | 6.01 – 6.26 | above zone |
| WTI Crude | 77.90 – 91.95 | 92.64 | just above zone | 82.90 – 95.33 | inside zone |
| Natural Gas | 2.84 – 3.15 | 3.22 | above zone | 2.78 – 3.01 | above zone |
Rates are excluded from cost basis by construction: structural shorts that never cross zero make the estimate unreliable. Russell 2000 and gold trade inside their dealer zone, meaning the aggregate epoch position there sits near flat P&L; VIX and the franc sit below theirs, the Dollar Index at the top edge, and the large-cap equity, crypto and remaining commodity books above. This is a descriptive P&L fact about the aggregate book. Tested in 2026, no covering response follows from a basis crossing, so do not treat any of these as triggers.
BOTTOM LINE
The decision this brief supports is where to size rate risk, not which way: the dealer short extreme and the leveraged crowd now sit together in the 5Y and the leveraged crowd keeps building in the 30Y, all measured before a long-end selloff and with PCE landing today, so treat belly and long-end books as the structurally fragile part of the curve while the front end has partly decompressed. In FX, the franc is the one book where the counterparty stretch is genuinely opposed; the rest of the week’s FX flow is size without a coherent dollar view.
Data: CFTC COT Report 2026-09-22 | Prices as of 2026-09-25 | Analysis window: 104 weeks
Smart Money Pulse - '26 W38
Rate Desks Went to an Extreme, Then the Tape Rallied Without Them
The heaviest money of the week went into the 2-Year Treasury. Dealer desks dropped two full steps, from a middling short position down to the bottom of their two-year range (z=-2.04), on one of the biggest position shifts on the board. They did it the day before the Federal Reserve raised rates.
For a regular portfolio that lands on the short and intermediate part of the bond sleeve, the part most people own through a core bond fund like BND or a short-dated fund like SHY without ever thinking about it. The professional money is arranged around the path of policy from here, not around the hike that already happened, and the next scheduled test is PCE, the Fed’s preferred inflation measure, on September 25.
All of this is a Tuesday photograph and you are reading it on Friday. Since the snapshot the Fed hiked and the market treated it as good news: the Nasdaq ran more than three percent, the S&P 500 gained close to two, Bitcoin added about seven, the fear gauge slid to the mid-14s, the dollar firmed and crude oil fell nearly ten percent. None of that tells you anyone moved their position. The next honest look at positioning is next week’s report.
This Week’s Positioning
The 2-Year Treasury: dealers sank to the floor of their range one day early

Dealers and the hedge fund crowd now sit at opposite ends of their own two-year histories here, which is as much tension as this data measures; both are still net short the contract itself, so the opposition is about where each group sits versus its own norm, not about one side betting against the other outright. Small traders, the cohort your own account belongs to, have gone the other way and largely backed out of this market. This describes how the front end of the bond market is arranged right now, nothing about where yields go.
Watch: the PCE inflation report on September 25. That is the first scheduled number that speaks directly to this book, and a regular investor feels it through short-dated bond funds and the cash sleeve.
The long end of the bond market: the fast money piled into the top of its range
At 30-year maturities the hedge fund crowd stepped two tiers higher in a single week and now sits near the top of its two-year range (z=+2.01), and it has been adding steadily for weeks. Dealers on the other side are nowhere near stretched, so this is a one-sided crowd rather than a standoff, and a crowded position is a fact about who owns what, not a signal about direction.
Watch: whether long-dated bond funds like TLT keep sliding now that the hike has landed. Long maturities are the most rate-sensitive thing in a typical portfolio and they are where this particular crowd lives.
The U.S. dollar: the stretch came out, and the big institutions and the fast money split
Dealers released a large piece of their dollar-index stretch this week on one of the bigger position shifts on the board, dropping out of a stretched posture back toward the middle. What is left is a genuine disagreement: the big asset managers are holding a dollar-bullish position near the high end of their range (z=+1.02) while the hedge fund crowd cut its own dollar bet to roughly flat and leans against the currency elsewhere.
Watch: whether the dollar index holds above 100 in the weeks after the hike. A firmer dollar quietly drags on unhedged international funds and on commodity prices; UUP is the closest thing a retail account can hold to the index itself.
Bitcoin: the speculative crowd got more crowded while dealers thinned out
The hedge fund crowd moved up another tier and now sits near the top of its two-year range (z=+1.61), while the dealer position, which in crypto is structurally a long, sits near the low end of its own range. That is the sharpest crowded-versus-thinning arrangement outside the bond market, and the tool reads it as crypto-specific rather than a broad risk signal, since nothing similar shows up in stock positioning.
Watch: whether Bitcoin holds the low-80,000s after this week’s run. Most people now own this through a spot ETF like IBIT rather than directly, which makes the position easy to forget about.
Everything else is doing less than the headlines suggest. Large-cap stock positioning drained back toward its average: S&P 500 dealers released their mild stretch entirely, and the Nasdaq book crossed the neutral line with dealers easing short and the fast money easing long, a repeat of an arrangement that has flipped back and forth for weeks without either side reaching a stretch. Small caps still carry the most one-sided speculative short on the equity board against an outright dealer long, though it eased a notch and is now background rather than news. Short-term rate futures, the market’s bet on where policy goes, remain the one contract where both professional groups sit at historical extremes in opposite corners, and nearly two fifths of the speculative side there is tied up in roll and calendar trades with no directional opinion. Currencies produced a lot of motion and little conclusion: the Japanese yen saw the largest weekly flow on the board for a second straight week, this time reversing the prior week’s reset, while the Mexican peso, Canadian dollar, euro, British pound, Swiss franc and Australian dollar all shuffled without landing anywhere decisive. Institutions kept showing unusually little interest in owning volatility protection. In commodities, the physical-market hedgers in copper backed off a tier of their hedge while the speculative crowd stayed leaning long, and gold, silver, crude and natural gas show the familiar hedger-versus-speculator gap with nothing at a genuine extreme.
Know Where You Stand
- Find out what your cash is actually paying now that the Fed has moved. Settlement funds, money-market funds and Treasury-bill holdings all reprice off the policy rate, and the most crowded professional books on the board sit in exactly these short-dated contracts; pull up the current yield on your brokerage’s default cash sweep and compare it against a bill fund like BIL, because the gap between the two is often wider than people assume.
- Crude oil fell almost ten percent since Tuesday, and that shows up in your account before it shows up at the pump. Energy is a meaningful slice of most total-market funds and the dominant one in a sector fund like XLE, so if your energy holdings lagged while the rest of the market rallied this week, this is a likely reason; nothing here calls for a trade, it is worth knowing where the drag came from.
- The stock side of this report is asking nothing of you this week, and that is the useful finding. Equity positioning is close to its two-year average across large caps, so there is no structural warning to act on; if you want a date rather than a feeling, PCE on September 25 is the next event that lands on the crowded books, and that is a reasonable point to review your allocation rather than reacting to the post-Fed rally.
Data: CFTC COT Report 2026-09-15 | Prices as of 2026-09-18 | 104-week lookback
Liquidity Trajectory '26 W38
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-09-15 | Generated: 2026-09-18 16:13 ET
EXECUTIVE SUMMARY
- The rates curve is the board’s stress center and duration got heavier into the Fed. UST 2Y dealers dropped two tiers from MODERATE to EXTREME SHORT (z -1.19 to -2.04, the 1.0th percentile) on the largest single repositioning of the week (WoW -92,432, event z -2.75^), while UST 10Y dealers extended their EXTREME SHORT to z -2.78 at the 0.0th percentile (WoW -84,962, flow z -2.00). Three of twenty-four groups sit above |z| 1.5 and all three are rates. The 2Y carries an options caveat (OptZ=+0.87), so read that extreme as a basis or directional footprint; the 10Y carries options corroboration (OptZ=-1.47), the one place the options-hedging hypothesis has support this week. Measured realized vol runs 1.13x the all-week average in the 2Y regime (n=58) and 1.00x in the 10Y (n=57).
- Leveraged funds are now crowded at the top of their range across three tenors at once. UST 5Y sits at the 99.0th percentile (lev z +2.08, adding ~51,105/wk), UST 30Y stepped two tiers from MODERATE to EXTREME LONG (z +1.37 to +2.01, 96.2nd percentile), and UST 2Y holds the 95.2nd percentile against the dealer extreme. All three remain net short in absolute contract terms; the z reads their posture versus their own range. SOFR 3M is the board’s only OPPOSED EXTREMES book, dealers at the 98.1st percentile on an outright +3,524,755 long against leveraged funds at the 4.8th percentile, with 37.7% of leveraged gross exposure in spread structure and an options caveat (OptZ=-3.20).
- The yen book turned over violently for a second straight week, this time in the opposite direction. JPY dealer flow printed the board’s largest deviation by a wide margin (event z -7.89^, flow z -7.27, WoW -129,093), carrying dealers from NEUTRAL to MODERATE SHORT yen (z +0.20 to -1.00) while leveraged funds swung two tiers the other way into an ELEVATED LONG yen at the 94.2nd percentile (z -0.29 to +1.63). The peso is the other aggressive FX book: MXN leveraged funds stepped to EXTREME LONG at the 99.0th percentile (z +2.06) on dealer flow the tool flags as outsized (event z +2.13^).
- Equity positioning rolled toward tech shorts while the small-cap squeeze setup eased a tier. Nasdaq dealers crossed from NEUTRAL into MODERATE SHORT (Consol z -0.21 to -0.62) as leveraged funds crossed the other way into MODERATE LONG (z +0.04 to +1.00), and S&P 500 dealers released MODERATE LONG back to NEUTRAL (z +0.58 to +0.40). Russell 2000 leveraged funds eased a tier to ELEVATED SHORT (z -2.03 to -1.52), against a genuine dealer long of +80,602 contracts at the 90.4th percentile carrying the equity concentration flag (25L/24S #). Group equity dealer average is +0.30z.
- Catalyst line: the FOMC hiked Wednesday Sep 17, two days after this Tuesday snapshot and one day before publication, landing directly on the SOFR, 2Y and 5Y books that already carry the board’s crowding. PCE follows Sep 25, seven days out, on the same front-end complex, and NFP lands Oct 2, fourteen days out, on the front end and the dollar ledger.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-09-15 Tuesday snapshot; the price moves below are current through Friday September 18 and run on a different clock. Price action does not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | +1.67% | ES=F, broad risk-on |
| Nasdaq | +3.33% | NQ=F, the strongest major |
| Russell 2000 | +0.33% | RTY=F, small caps lagged |
| VIX | -13.78% | ^VIX 14.81, fear gauge back to the mid-14s |
| Bitcoin | +7.13% | crypto led the tape |
| Ether | +9.73% | the largest gain on the board |
| UST 10Y | -0.40% | ZN=F futures down = yields up |
| UST 2Y | -0.39% | ZT=F futures down = front-end yields up |
| Dollar Index | +0.55% | DX-Y.NYB, USD up |
| JPY | -0.67% | 6J=F down = yen down vs dollar |
| Copper | +5.47% | HG=F, metals complex firm |
| WTI Crude | -9.64% | CL=F, the largest decline on the board |
The FOMC decision was released Wednesday and the Fed hiked, and the tape read it as a growth-positive outcome rather than a tightening scare: front-end and long-end futures both slipped, tech and crypto rallied hard on renewed AI chip demand and post-CLARITY regulatory clarity, the fear gauge collapsed and the dollar firmed. Crude broke sharply lower on the same stretch. All of this is price action after the Tuesday snapshot and none of it confirms dealer, leveraged fund or asset manager repositioning. The next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 2Y | REGIME STEP TO EXTREME + OPPOSED EXTREMES | -1.19 to -2.04 (Δ -0.85) | +2.48 to +2.37 (Δ -0.11) | dlr MODERATE to EXTREME SHORT; lev EXTREME LONG (held) | dealer 1.0th pctl, net -536,280, WoW -92,432, event z -2.75^; lev 95.2nd pctl but net -1,294,575, still short in absolute terms; AM z -1.61 at 8th pctl; small traders z -1.72, washed out; RV 1.13x (n=58); OptZ=+0.87 caveat |
| 2 | UST 10Y | DEEPEST DEALER SHORT ON THE BOARD | -2.29 to -2.78 (Δ -0.49) | +0.17 to +0.40 (Δ +0.23) | dlr EXTREME SHORT (held); lev NEUTRAL (held) | dealer 0.0th pctl, net -719,408, WoW -84,962, flow z -2.00, event z -1.94^; AM long 99th pctl (z +1.84) on +2,634,980; Other Reportables z -1.97 at 0th pctl; RV 1.00x (n=57), no amplification; OptZ=-1.47 corroborates |
| 3 | SOFR 3M | OPPOSED EXTREMES, BOTH SIDES HELD | +2.64 to +2.41 (Δ -0.23) | -2.16 to -2.08 (Δ +0.08) | dlr EXTREME LONG (held); lev EXTREME SHORT (held) | dealer 98.1st pctl, outright +3,524,755, WoW -168,270; lev 4.8th pctl on -2,774,148; AM z -1.97 at 1st pctl; 37.7% lev gross in spread structure; OptZ=-3.20 caveat; 92L/92S # |
| 4 | JPY | BOARD-LARGEST FLOW, BOTH COHORTS CROSSED | +0.20 to -1.00 (Δ -1.20) | -0.29 to +1.63 (Δ +1.92) | dlr NEUTRAL to MODERATE SHORT; lev NEUTRAL to ELEVATED LONG | event z -7.89^, flow z -7.27, WoW -129,093; dealer 18.3rd pctl, net -168,570 (short yen); lev 94.2nd pctl, net +23,170 long yen, adding ~35,373/wk; AM z +0.45; Other Reportables z +1.00; OptZ=-0.95 |
| 5 | UST 5Y | LEV CROWDED LONG, TOP OF RANGE | -1.47 to -1.45 (Δ +0.02) | +1.98 to +2.08 (Δ +0.10) | dlr MODERATE SHORT (held); lev ELEVATED to EXTREME LONG | lev 99.0th pctl, adding ~51,105/wk, net -1,986,928 still short outright; dealer 5.8th pctl, net -855,342, flow z +0.03; AM z -1.23 at 8th pctl; small traders z -1.58; RV 1.11x (n=245); OptZ=-1.11 |
| 6 | UST 30Y | LEV STEPPED TWO TIERS AT THE LONG END | -0.87 to -0.69 (Δ +0.18) | +1.37 to +2.01 (Δ +0.64) | dlr MODERATE SHORT (held); lev MODERATE to EXTREME LONG | lev 96.2nd pctl, adding ~29,986/wk, net -211,735; dealer 26.9th pctl, net -241,670, 4 straight weeks of net increase; AM z -0.96; Other Reportables z -2.44 at 1st pctl; top-4 35.1%; OptZ=+0.75 |
| 7 | Nasdaq (Consol) | REGIME TRANSITION, COHORTS CROSSED IN OPPOSITE DIRECTIONS | -0.21 to -0.62 (Δ -0.41) | +0.04 to +1.00 (Δ +0.96) | dlr NEUTRAL to MODERATE SHORT; lev NEUTRAL to MODERATE LONG | dealer 30.8th pctl, net -69,952, WoW -12,350, flow z -1.80^, event z -1.49; lev 84.6th pctl but net -13,052, short in absolute terms, adding ~7,494/wk; AM z -0.08; OptZ=-1.74; Mini dlr -0.39 to -0.82 (Δ -0.43), Mini small traders z +0.84 at 83rd pctl |
| 8 | MXN | LEV STEPPED TO EXTREME ON OUTSIZED DEALER FLOW | -1.85 to -1.06 (Δ +0.79) | +1.86 to +2.06 (Δ +0.20) | dlr ELEVATED to MODERATE SHORT; lev ELEVATED to EXTREME LONG | event z +2.13^, flow z +2.70, WoW +34,661; dealer 13.5th pctl, net -93,766 (short peso); lev 99.0th pctl, net +90,008 long peso, adding ~7,105/wk; AM z +0.58; top-4 62.5%; OptZ=+0.60 |
| 9 | Russell 2000 | LEV SHORT EASED A TIER, DEALER LONG CONCENTRATED # | +1.26 to +1.11 (Δ -0.15) | -2.03 to -1.52 (Δ +0.51) | dlr MODERATE LONG (held); lev EXTREME to ELEVATED SHORT | dealer 90.4th pctl, genuine outright long +80,602, top-4 18.3% on a flagged 25L/24S # book; lev 5.8th pctl, net -97,203; AM z -0.42; Other Reportables z -1.22 at 6th pctl; RV 0.92x (n=102); OptZ=-0.61 |
| 10 | USD Index | STRETCH RELEASED, BUY-SIDE SPLIT | -1.90 to -0.99 (Δ +0.91) | +1.07 to -0.15 (Δ -1.22) | dlr ELEVATED to MODERATE SHORT; lev MODERATE LONG to NEUTRAL | flow z +2.48, WoW +11,642, event z +1.48; dealer 21.2nd pctl, net -15,204; AM z +1.02 at 78th pctl holds the DXY long; Other Reportables z +1.35 at 89th pctl; top-4 77.5% on a 6L/0S ledger; OptZ=+0.00 caveat |
| 11 | CHF | LEV CROWDED SHORT DEEPENED | +0.96 to +1.43 (Δ +0.47) | -1.32 to -1.54 (Δ -0.22) | dlr MODERATE LONG (held); lev MODERATE to ELEVATED SHORT | dealer 90.4th pctl, net +66,512 (genuine long franc); lev 6.7th pctl, net -14,964; small traders z -1.49 at 7th pctl; RV 1.13x (n=191); OptZ=+1.20, options-implied dealer delta stretched long; top-4 53.6% |
| 12 | Copper | COMMERCIALS RELEASED A TIER, MM STILL CROWDED | -1.78 to -1.21 (Δ +0.57) | +1.77 to +1.02 (Δ -0.75) | Commercials ELEVATED to MODERATE SHORT; Managed Money ELEVATED to MODERATE LONG | event z +1.67^, flow z +2.16, WoW +13,954; Commercials 10.6th pctl, net -97,911 hedge; Managed Money 80.8th pctl, net +65,541 long; Swap Dealers z -0.54; Other Reportables z +1.50 at 96th pctl |
| 13 | CAD | OUTSIZED FLOW, FOURTH STRAIGHT WEEKLY DECLINE | -0.50 to -0.92 (Δ -0.42) | +0.17 to +0.97 (Δ +0.80) | dlr now MODERATE SHORT (transition); lev NEUTRAL to MODERATE LONG | event z -2.09^, flow z -2.46, WoW -33,493; dealer 18.3rd pctl, net +48,614 (still a genuine long CAD); lev 78.8th pctl, net -39,022 short CAD; AM z +0.97 at 80th pctl; top-4 59.7%; OptZ=+0.42 |
| 14 | Bitcoin | LEV CROWDED LONG, DEALER STRUCTURAL LONG THINNING | -1.03 to -0.93 (Δ +0.10) | +1.32 to +1.61 (Δ +0.29) | dlr MODERATE SHORT (held); lev MODERATE to ELEVATED LONG | dealer 10.6th pctl, net +3,419 (structural long near its range low); lev 96.2nd pctl on a net of -6,354, below zero outright, thin 26L/42S # book; AM z -1.84 at 9th pctl; top-4 59.6%; OptZ=-0.22 |
| 15 | VIX | PROTECTION DEMAND LOW, AM VOL SELLING AT AN EXTREME | +0.56 to +0.91 (Δ +0.35) | +0.52 to +0.76 (Δ +0.24) | dlr MODERATE LONG (held); lev MODERATE LONG (held) | dealer 83.7th pctl, net +62,801 long VIX = low protection demand; AM net short vol at z -2.31, the board’s most negative AM reading; small traders net long VIX z +1.43 at 92nd pctl, a crowded protection bid; 29.3% of lev gross in spread structure; OptZ=+0.00 |
| 16 | S&P 500 (Consol) | REGIME RELEASE TO NEUTRAL | +0.58 to +0.40 (Δ -0.18) | -0.13 to +0.55 (Δ +0.68) | dlr MODERATE LONG to NEUTRAL; lev NEUTRAL to MODERATE LONG | dealer 57.7th pctl, net -681,795 (short in absolute terms), WoW -18,973, covering ~22,650/wk over 4 weeks; lev 69.2nd pctl on -311,831; AM z -0.46; OptZ=-1.68; E-Mini dlr +0.40 to +0.23 (Δ -0.17) |
| 17 | Ether | REGIME TRANSITION, INTRA-CRYPTO ROTATION | +0.26 to +0.53 (Δ +0.27) | +0.42 to +0.34 (Δ -0.08) | dlr NEUTRAL to MODERATE LONG; lev NEUTRAL (held) | dealer 70.2nd pctl, net +10,571 (structural long), WoW +1,168; lev 57.7th pctl on -7,722; AM z -1.42 at 12th pctl; top-4 75.2% on a thin 5L/10S book; OptZ=-0.53 |
| 18 | AUD | LEV CROWDED LONG STEPPED A TIER | -0.52 to -0.58 (Δ -0.06) | +1.26 to +1.58 (Δ +0.32) | dlr MODERATE SHORT (held); lev MODERATE to ELEVATED LONG | dealer 23.1st pctl, net -38,303 (short AUD); lev 95.2nd pctl, net +61,135 long AUD, adding ~2,134/wk; AM z -0.62; small traders 42.2% of OI, the largest small-trader share on the board; top-4 45.5% |
| 19 | Natural Gas | SWAP DEALER EXTREME, REST QUIET | +0.31 to +0.22 (Δ -0.09) | -0.85 to -0.89 (Δ -0.04) | Commercials NEUTRAL (held); Managed Money MODERATE SHORT (held) | Swap Dealers z +2.31 at 99th pctl on +223,515; Commercials 57.7th pctl, net -17,103; Managed Money net -100,024 short, aligned with the hedge; 49.6% of OI sits in the Managed Money book |
| 20 | EUR | LEV CROWDED SHORT (dollar-bull) | +0.68 to +0.70 (Δ +0.02) | -1.19 to -1.01 (Δ +0.18) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -258,080 (short euro, high end of its short range, not a long), 72.1st pctl; lev 23.1st pctl short euro; AM +251,698 holds the euro long; small traders 20.5% of OI; OptZ=-0.13 |
| 21 | GBP | LEV CROSSED TO SHORT STERLING | +0.62 to +0.60 (Δ -0.02) | +0.04 to -1.12 (Δ -1.16) | dlr MODERATE LONG (held); lev NEUTRAL to MODERATE SHORT | dealer 68.3rd pctl, net +68,223 (genuine long GBP); lev 13.5th pctl, net +18,878 still long outright, reducing ~9,563/wk; AM z -0.52; small traders 35.6% of OI; OptZ=+0.54 |
| 22 | Gold | HEDGERS HIGH, SPECULATORS FLAT | +0.92 to +1.01 (Δ +0.09) | +0.03 to -0.01 (Δ -0.04) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 73.1st pctl, net -26,250 hedge; Managed Money net +137,060 long at 58.7th pctl; Swap Dealers z -0.90 at 24th pctl; Other Reportables 39.4% of OI, the largest on the board |
| 23 | Silver | HEDGERS HIGH, MM SHORT OF ITS RANGE | +1.07 to +1.06 (Δ -0.01) | -0.81 to -0.93 (Δ -0.12) | Commercials MODERATE LONG (held); Managed Money MODERATE SHORT (held) | Commercials 76.0th pctl, net -17,407 hedge; Managed Money 26.9th pctl, net +12,632 still long outright; Swap Dealers z +0.96 at 83rd pctl; Other Reportables z -1.58 at 3rd pctl |
| 24 | WTI Crude | QUIET, HEDGERS NET LONG | +0.75 to +0.71 (Δ -0.04) | +0.41 to +0.32 (Δ -0.09) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 78.8th pctl, net +307,409 (unusually net long for this cohort); Managed Money net +106,279 at 70.2nd pctl; Swap Dealers z -0.47; deep trader book (67L/60S); top-4 9.3%, the least concentrated on the board |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
Read this as one curve and the shape is unambiguous: dealers are carrying the board’s deepest short posture across the note complex while leveraged funds sit crowded at the top of their own range at three separate tenors. The 2Y is the week’s news, a two-tier step into extreme territory on the single largest repositioning of the week, and it arrived in the days before a Fed decision rather than after it. The 10Y is the standing level, deeper still and unchanged in character. The front-to-back gradient now has stress concentrated in duration rather than at the policy-sensitive front, which keeps the positioning stress concentrated in duration.
Three caveats carry over unchanged and none of them has softened. A large share of leveraged gross exposure in SOFR sits in spread and roll structures, so the directional read there overstates conviction. The options-implied dealer delta does not corroborate either the SOFR or the 2Y futures extreme, which makes both a basis or directional footprint rather than an options-hedging story; the 10Y is the sole exception, where the options book does support the read. And the measured realized-vol ratios across the complex are modest to flat, so the short-gamma vol amplification inference stays a hypothesis and nothing more.
The counterparty structure is worth stating plainly. In the 2Y, dealers and leveraged funds hold genuinely opposed postures versus their own ranges, and in SOFR they hold the only both-sides extreme on the board, which is maximum positioning tension in the structural sense. That is squeeze fuel if either side is forced to move, though it is market structure and not a directional call. Across the 5Y and 30Y, dealers and leveraged funds are drifting the same way rather than opposing each other, which compresses rather than builds that tension even as the leveraged level extends. Measured asset managers hold the mirror duration long in the 10Y near the top of their range and sit washed out at the bottom of theirs in the 2Y, 5Y and SOFR, and small traders are washed out across the note complex, the contrarian mirror of a crowded extreme. Positioning context only, not a forecast.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
The dollar book does not tell one clean story this week and that is itself the finding. Leveraged funds lean short the dollar against most crosses, holding the yen, the Aussie and the peso long while the euro and the franc are the two shorts, and they simultaneously released their small Dollar Index long to neutral. Asset managers hold the opposite index posture, long DXY near the top of their range while also holding the euro long outright. Cross-check that against the majors and the buy-side is genuinely split rather than expressing one coherent dollar view, which is worth a second look rather than a headline.
The yen produced the board’s most violent flow for the second consecutive week, and it reversed direction: last week the book reset one way, this week both cohorts crossed back the other. Dealers ended the week short yen while leveraged funds crossed into a crowded long. The peso remains the other aggressive book, with leveraged funds pressing their long a tier higher against a dealer short that has released two tiers of its own stretch, so the two sides are no longer opposed at the same intensity. The Canadian dollar carries outsized flow for a fourth straight week of dealer net decline, and mind the sign discipline there: the dealer regime reads short against its range while the outright position is still a genuine long, and leveraged funds hold the actual short. The franc is the FX book where the level and the counterparty structure line up best, dealers holding a real long high in their range against a leveraged short that deepened a tier, with the options-implied dealer delta stretched the same way. Sterling and the Australian dollar moved only on the leveraged side. In the euro, dealers read as a moderate long regime while remaining short the contract at the high end of their short range, so dealers and leveraged funds sit on the same side and the euro long belongs to asset managers.
The franc carries analog data. Five prior MODERATE LONG DELTA episodes returned a median -1.19% over the following four weeks, 1 of 4 with a resolved outcome bullish, against an unconditional base rate of +0.04% median and 51% bullish across all 885 weeks. That is a mild one-sided tilt on four resolved episodes, which is historical context and not a signal, and the window is anchored to Tuesday, so three sessions of any such window have already elapsed.
Equities (S&P 500, Nasdaq, Russell 2000)
The equity board rotated rather than stretched. Nasdaq is the transition: both cohorts crossed the neutral boundary in opposite directions in a single week, dealers into a moderate short and leveraged funds into a moderate long, on flow the tool flags as unusually large for the event phase. Neither side is stretched yet, and the leveraged fund position is still short in absolute contract terms, but the divergent trend is the configuration that builds a crowded trade if it extends. Note that Nasdaq Mini small traders sit near the high end of their own range, the classic crowded contrarian posture, context only. The S&P 500 did the opposite and released its dealer stretch back to the mean after four weeks of steady short covering, leaving a book where the flow was large and the level says nothing. Dealers remain net short the S&P 500 contract in absolute terms throughout, as they do in Nasdaq.
Russell 2000 stays the sharpest one-sided book on the equity board, though it eased. Dealers hold a genuine outright long high in their two-year range against a leveraged short that lifted one tier off extreme, and the dealer side carries the only equity concentration flag, meaning that book is thin if it has to turn. The counterparty tension is real but a tier less acute than last week, and the measured realized vol for that regime shows no amplification.
Russell carries analog data. Five prior MODERATE LONG DELTA episodes returned a median +5.83% over the four weeks that followed, 4 of 5 bullish, against an unconditional base rate of +1.09% median and 60% bullish across all 476 weeks. The median runs well above the base rate and the hit rate edges it, but on five overlapping episodes this is historical context, not a signal, and the same three-session elapse applies.
Crypto (Bitcoin, Ether)
The intra-crypto split widened. Bitcoin dealers sit low in their range on a structural long that keeps thinning, against leveraged funds crowded a tier higher near the top of theirs on a thin and concentration-flagged book, which is the cleanest crowded-long-versus-thinning-dealer configuration outside rates. Ether crossed the other way into a moderate dealer long. Standing caveat, unchanged: crypto dealers are structurally net long, so a negative z means the dealer long sits at the low end of its historical range rather than an outright short, and both books are thin enough that trader counts matter as much as the z. Measured asset managers are washed out in both names, more so in Bitcoin. The tool flags this as a crypto-specific divergence rather than a broad risk-off read, since equity positioning shows nothing comparable.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Copper is the only commodity that cleared the gate on its own terms. Commercials released a tier of their hedge stretch on flow the tool flags as outsized for the event phase, while Managed Money stepped down a tier but stayed crowded long against them. That is the canonical hedger-versus-speculator tension and it remains genuinely opposed, just less acute than last week. Other Reportables sit near the top of their range there too, an unusually large mid-size presence for this market. Positioning state only.
Natural gas carries one standing oddity, a Swap Dealer book pinned at the top of its range while Commercials sit mid-range and Managed Money runs short alongside the hedge. Gold, silver and WTI crude sat quiet: hedgers moderately high versus their own ranges in all three, speculators flat to modestly short, and no cohort near a boundary. Crude runs the least concentrated book on the board on a deep trader count, so its readings carry more participation weight than the others even when nothing moves.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (Consol) | 6,644.84 – 6,845.78 | 7,714.50 | above zone | 7,095.91 – 7,315.31 | above zone |
| Nasdaq (Consol) | 28,986.82 – 29,977.37 | 29,922.75 | inside zone | 28,376.65 – 29,432.92 | above zone |
| Russell 2000 | 2,825.62 – 2,924.76 | 2,882.10 | inside zone | 2,854.08 – 2,951.17 | inside zone |
| VIX | 15.60 – 19.04 | 14.81 | below zone | 14.30 – 16.03 | inside zone |
| Bitcoin | 76,336.57 – 82,612.74 | 80,996.99 | inside zone | 72,561.09 – 78,932.08 | above zone |
| Ether | 2,272.71 – 2,514.97 | 2,631.50 | above zone | 2,207.51 – 2,426.08 | above zone |
| Gold | 4,168.40 – 4,382.55 | 4,415.30 | above zone | 3,972.55 – 4,185.25 | above zone |
| Silver | 57.62 – 63.75 | 66.86 | above zone | 65.01 – 72.12 | inside zone |
| Copper | 5.71 – 5.97 | 6.72 | above zone | 5.84 – 6.11 | above zone |
| WTI Crude | 77.61 – 91.70 | 95.66 | above zone | 80.91 – 93.37 | above zone |
| CHF | 1.23 – 1.25 | 1.23 | at the low edge | 1.24 – 1.26 | below zone |
Rates are excluded from cost basis by construction: structural shorts that never cross zero make the estimate unreliable. Three books trade inside their dealer zone this week (Nasdaq, Russell 2000, Bitcoin), meaning the aggregate epoch position there sits near flat P&L; VIX and the franc sit at or below theirs, and the commodity, large-cap equity and crypto books above. This is a descriptive P&L fact about the aggregate book. Tested in 2026, no covering response follows from a basis crossing, so do not treat any of these as triggers.
BOTTOM LINE
The decision this brief supports is sizing, not direction: the note complex now carries a dealer short extreme, a leveraged fund crowd at the top of its range across three tenors and the board’s only both-sides extreme, all of it measured before a Fed hike that has since landed and with PCE seven days out. Treat rate-book risk as structurally fragile rather than directionally informative, and read the yen and peso flows as the FX books most likely to move on size rather than view.
Data: CFTC COT Report 2026-09-15 | Prices as of 2026-09-18 | Analysis window: 104 weeks
Smart Money Pulse - '26 W37
The Bond Desks Dug In Six Days Before the Fed
The single most stretched position anywhere in this week’s report is in 10-Year Treasuries, where dealer desks pushed their short to the very bottom of its two-year range (z=-2.29) for a fourth straight week in the same direction. The big asset managers hold the other side of that trade near the top of their own range. Nobody is hedging this quietly; both sides keep adding.
For a normal portfolio that lands squarely on the bond sleeve. Intermediate and long-dated bond funds are where this book lives, and the professional money is arranged around the September 17 Federal Reserve rate decision rather than around anything that has already happened. August consumer inflation, released Wednesday, failed to cool, which is what turned a crowded rate position into a tense one.
Remember this is Tuesday’s snapshot and you are reading it on Friday. Since then the whole Treasury curve sold off with the longest maturities worst, small caps slid about two percent, the dollar firmed and crude oil pushed through $100. That is price action, not evidence that anyone moved their position; the next real look at positioning is next week’s report.
This Week’s Positioning
Copper: where commercial hedgers sit vs their 2-year range
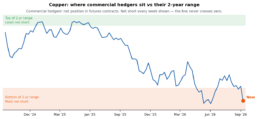
The producers and merchants who hedge physical copper stepped deeper into that hedge this week, down near the low end of their two-year range (z=-1.78), on one of the largest weekly shifts anywhere in the report. Managed Money, the speculative crowd, went the other way and now sits at the top of its own range, so the two groups are as far apart as this data gets. Copper trades around $6.55 after a strong run, and this arrangement describes who is holding what, nothing about where the price goes next.
Watch: whether copper holds above $6.50 through the Fed decision. Copper exposure shows up for most people inside a broad materials or commodity fund rather than through CPER directly.
Short-term rate futures: both sides pinned at the extremes
SOFR futures, the market’s bet on short-term interest rates, are the one contract where the dealers and the hedge fund crowd are both at historical extremes at the same time, in opposite corners. Read that as maximum tension into next week’s Fed meeting rather than as a view on rates, and discount it further: nearly two fifths of the speculative side is tied up in roll and calendar trades that carry no directional opinion at all.
Watch: the Fed statement on September 17. This is the book most directly exposed to a surprise in the language about the path of rates, and a regular investor feels it through short-dated bond funds like SHY and cash-like holdings.
The Japanese yen: the whole book got wiped clean
The yen saw the largest weekly repositioning of any market in the report, and it moved both professional groups at once: dealers crossed from a modest long into a net short yen position, while hedge funds abandoned a stretched short and went back to roughly flat. Both cohorts now lean the same way, mildly against the yen, which leaves this the least stale currency position on the board.
Watch: the dollar-yen rate into the Bank of Japan and Fed meetings. Japan is a top weight in almost every international index fund, so this one reaches a standard portfolio through the foreign sleeve.
Large-cap stocks: the two indexes stopped pulling apart
S&P 500 dealers moved up out of neutral into a mildly stretched posture on repositioning the tool flags as unusually large with no scheduled event behind it, while Nasdaq dealers came back down into neutral from the short side. The tech divergence that ran for several weeks has drained out of the futures book. The one exception is the Nasdaq options-implied reading, which is the most stretched figure on the board and sits far from where the futures say, so the tech story this week is an options-book fact rather than a positioning one.
Watch: how QQQ trades relative to SPY into the Fed decision. Small traders, the cohort your own account belongs to, are crowded near the high end of their range in Nasdaq, which is often where the crowd gets it wrong.
Everything else is holding a pose it has held for weeks. Small caps still carry the most one-sided speculative short in the report against an outright dealer long, unchanged from last week and now background rather than news. The dollar index stays pinned with dealers stretched short against a fast-money long, a consistently dollar-bullish lean that also shows up as a crowded short in the euro, and the Mexican peso holds the same maximum-tension setup. Institutional appetite for volatility protection faded again, with the big asset managers showing little interest in owning it while small traders sit near the top of their own range holding protection. In Bitcoin, the structural dealer long keeps sitting at the floor of its two-year range while the hedge fund crowd stays near the top of its own. The British pound, Swiss franc, Canadian dollar and Australian dollar all shuffled without reaching a stretch, and gold, silver, crude and natural gas show the usual hedger-versus-speculator gap with nothing at a genuine extreme.
Know Where You Stand
- Protection is unusually cheap right now, and that is a fact about pricing, not a recommendation to buy it. The fear gauge sits near 15.9 with institutions net short volatility, so if a hedge on an SPY position was ever part of your plan, this is the part of the cycle where it costs least; if hedging is not part of your plan, the useful version of this is simply knowing you are unhedged going into September 17.
- Your foreign holdings carry a dollar bet you did not choose. The professional money is leaning dollar-bullish through several currencies at once, and a stronger dollar quietly drags on unhedged international funds like VXUS and on commodity exposure; worth checking whether your foreign sleeve is currency-hedged, because most default options are not.
- Check whether tech has crept up as a share of your account. Small traders are crowded at the high end of their range in Nasdaq futures, and the same drift happens passively in retirement accounts when a few large names run; pull up your actual QQQ or total-market weighting rather than assuming last year’s allocation still holds.
Data: CFTC COT Report 2026-09-08 | Prices as of 2026-09-11 | 104-week lookback
Liquidity Trajectory '26 W37
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-09-08 | Generated: 2026-09-11 15:50 ET
EXECUTIVE SUMMARY
- Duration is the board’s stress center and it deepened. UST 10Y dealers pushed further into EXTREME SHORT (z -2.03 to -2.29), the 0.0th percentile of the two-year range, on a fourth straight week of net decline (WoW -47,349, net -634,446). This is the one dealer extreme on the board carrying options corroboration rather than a caveat (OptZ=-1.07), so the options-book read has support this week. Measured realized vol in this regime runs 1.00x the all-week average (n=57 overlapping weeks), so no vol amplification is evident in this market’s history. Measured asset managers hold the other side at the 94th percentile (AM z +1.65).
- SOFR 3M remains the board’s only both-sides extreme and both sides widened. Dealers sit at the 99.0th percentile on an outright +3,693,025 contract long (WoW +313,707, flow z +1.59^) against leveraged funds at the 1.9th percentile, whose regime slipped a tier from ELEVATED to EXTREME SHORT (z -1.97 to -2.16). Measured asset managers are washed out at the 0th percentile (AM z -2.23), 39% of leveraged gross exposure is spread structure, and the options-implied dealer delta carries a caveat (OptZ=-1.77), so read the futures extreme as a basis or directional footprint, not gamma.
- Copper produced the week’s cleanest commodity development: a regime step to ELEVATED SHORT for Commercials (z -1.23 to -1.78, 1.9th percentile) on the third-largest relative flow on the board (flow z -2.29^), against Managed Money stepping up to ELEVATED LONG (z +1.41 to +1.77). That is a full opposed-extremes book with a concentration flag (28L/35S #), and it is positioning state only.
- The yen book reset both cohorts on the board’s largest flow (flow z -6.88^, WoW -118,798). Dealers crossed the zero line into net short yen (-39,477) and leveraged funds released an ELEVATED SHORT back to NEUTRAL (z -1.73 to -0.29). Elsewhere in FX the dollar story held its shape: USD Index dealers stayed ELEVATED SHORT (z -1.90, 5.8th percentile) on a one-sided, concentration-flagged ledger (top-4 64.7%, 7L/0S #) with measured realized vol at 1.18x the all-week average (n=35), the highest measured realized-vol ratio on the board, and the buy-side long DXY.
- Catalyst line: August CPI printed Wednesday Sep 9 and inflation failed to cool, and the FOMC decision lands Sep 17, six days out, directly on the SOFR, 2Y and 5Y books that already carry the board’s crowding. PCE follows Sep 25, fourteen days out, on the same front-end complex. NFP sits outside the two-week window on Oct 2.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-09-08 Tuesday snapshot; the price moves below are current through Friday September 11 and run on a different clock. Price action does not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | -0.18% | ES=F ~7,667 |
| Nasdaq | -0.41% | NQ=F ~29,419 |
| Russell 2000 | -1.91% | RTY=F ~2,907, the weakest major |
| VIX | +0.83% | ^VIX 15.85 |
| Bitcoin | -1.52% | ~77,235 |
| Ether | +2.21% | ~2,540 |
| UST 10Y | -1.31% | ZN=F futures down = yields up |
| UST 2Y | -0.58% | ZT=F futures down = front-end yields up |
| UST 30Y | -1.95% | ZB=F futures down = long-end yields up |
| Dollar Index | +0.29% | DX-Y.NYB 99.12, USD up |
| JPY | +0.65% | 6J=F up = yen up vs dollar |
| CAD | -0.23% | 6C=F down = Canadian dollar down vs USD |
| Copper | -2.86% | HG=F 6.55 |
| WTI Crude | +8.10% | CL=F 100.57 |
August CPI was released Wednesday and inflation did not cool, and the tape since the snapshot has traded a rate-hike repricing on top of an oil spike: the whole curve sold off with the long end worst, small caps slumped hardest of the majors, the dollar firmed and crude ran through 100. All of this is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund, asset manager, Commercial or Managed Money repositioning. The next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 10Y | DEALER EXTREME SHORT, DEEPENED | -2.03 to -2.29 (Δ -0.26) | -0.26 to +0.17 (Δ +0.43) | dlr EXTREME SHORT (held, deeper); lev NEUTRAL (held) | dealer 0.0th pctl, net -634,446, WoW -47,349; 4 straight weeks of dealer net decline (avg -40,045/wk); AM long 94th pctl (z +1.65); RV 1.00x (n=57), no amplification; OptZ=-1.07 corroborates; small traders washed out (z -1.68) |
| 2 | SOFR 3M | OPPOSED EXTREMES, BOTH WIDER | +2.43 to +2.64 (Δ +0.21) | -1.97 to -2.16 (Δ -0.19) | dlr EXTREME LONG (held); lev ELEVATED to EXTREME SHORT | flow z +1.59^, WoW +313,707; dealer 99.0th pctl, net +3,693,025; lev 1.9th pctl, net -2,803,445; AM z -2.23 at 0th pctl; 39% lev gross in spread structure; OptZ=-1.77 caveat; 93L/89S # |
| 3 | UST 2Y | LEV EXTREME LONG, REAL MONEY WASHED OUT | -1.11 to -1.19 (Δ -0.08) | +2.66 to +2.48 (Δ -0.18) | dlr MODERATE SHORT (held); lev EXTREME LONG (held) | lev 96.2nd pctl but still net short in absolute terms (-1,290,479), unwinding ~17,771/wk; dealer 13.5th pctl, net -443,848; AM z -2.18 at 3rd pctl; small traders z -1.76, washed out; OptZ=+0.54 |
| 4 | Copper | REGIME STEP + OPPOSED EXTREMES # | -1.23 to -1.78 (Δ -0.55) | +1.41 to +1.77 (Δ +0.36) | Commercials MODERATE to ELEVATED SHORT; Managed Money MODERATE to ELEVATED LONG | flow z -2.29^, WoW -14,843; Commercials 1.9th pctl, net -111,865 hedge; Managed Money 99.0th pctl, net +82,154; Swap Dealers z -1.36; Other Reportables z +1.63 at 98th pctl; 28L/35S # |
| 5 | Russell 2000 | LEV EXTREME SHORT vs OUTRIGHT DEALER LONG # | +1.39 to +1.26 (Δ -0.13) | -2.07 to -2.03 (Δ +0.04) | dlr MODERATE LONG (held); lev EXTREME SHORT (held) | dealer 95.2nd pctl, outright long +89,619, top-4 21%, 26L/22S #; lev 1.9th pctl, net -110,147, still reducing ~4,288/wk; AM z -0.45; RV 0.93x (n=101); OptZ=-0.39 |
| 6 | UST 5Y | LEV CROWDED LONG, BOTH SIDES STRETCHING | -1.12 to -1.47 (Δ -0.35) | +1.74 to +1.98 (Δ +0.24) | dlr MODERATE SHORT (held); lev ELEVATED LONG (held) | dealer 4.8th pctl, net -855,908, WoW -41,473; lev 99.0th pctl, still net short in absolute terms (-2,066,289), adding ~21,970/wk; AM z -1.07; RV 1.11x (n=244); OptZ=-0.50 |
| 7 | USD Index | DEALER STRETCHED SHORT + CONCENTRATION # | -1.92 to -1.90 (Δ +0.02) | +1.10 to +1.07 (Δ -0.03) | dlr ELEVATED SHORT (held); lev MODERATE LONG (held) | dealer 5.8th pctl, net -26,846; buy-side long DXY (lev +6,186, AM z +1.10) = bullish USD; MEASURED VOL 1.18x (n=35); OptZ=+0.00 caveat; top-4 64.7%, 7L/0S # |
| 8 | MXN | OPPOSED EXTREMES | -1.81 to -1.85 (Δ -0.04) | +1.64 to +1.86 (Δ +0.22) | dlr ELEVATED SHORT (held); lev ELEVATED LONG (held) | dealer 3.8th pctl, net -128,427 (short peso); lev 99.0th pctl, net +82,101 long peso, adding ~5,577/wk; AM z +0.99; RV 0.97x (n=37), no amplification; OptZ=+0.60 caveat; 4 straight weeks of dealer net decline |
| 9 | JPY | BOARD-LARGEST FLOW, BOTH COHORTS RESET | +1.33 to +0.20 (Δ -1.13) | -1.73 to -0.29 (Δ +1.44) | dlr MODERATE LONG to NEUTRAL; lev ELEVATED SHORT to NEUTRAL | flow z -6.88^, WoW -118,798, the largest relative flow on the board; dealer net crossed zero to -39,477 (short yen), having been above zero a week ago; lev net -49,098; AM z -0.51; Other Reportables 18.5% of OI; OptZ=-0.83 |
| 10 | S&P 500 (Consol) | REGIME TRANSITION ON OUTSIZED FLOW | +0.23 to +0.58 (Δ +0.35) | +0.23 to -0.13 (Δ -0.36) | dlr NEUTRAL to MODERATE LONG; lev NEUTRAL (held) | flow z +1.62^, WoW +38,411 without a calendar catalyst; dealer 69.2nd pctl, net -662,822 (short in absolute terms, at the high end of its short range); AM +914,443 long; OptZ=-0.33; E-Mini dlr +0.08 to +0.40 (Δ +0.32), lev +0.45 to +0.14 (Δ -0.31) |
| 11 | Nasdaq (Consol) | REGIME TRANSITION BACK TO NEUTRAL | -0.61 to -0.21 (Δ +0.40) | +0.82 to +0.04 (Δ -0.78) | dlr MODERATE SHORT to NEUTRAL; lev MODERATE LONG to NEUTRAL | flow z +1.79^, WoW +12,113; dealer 51.0th pctl, net -57,602; OptZ=-2.39, the board’s most stretched options-implied dealer delta; AM z +0.57; Mini dlr -0.80 to -0.39 (Δ +0.41), small traders z +1.50 at 95th pctl |
| 12 | CAD | REGIME TRANSITION ON OUTSIZED FLOW | -0.05 to -0.50 (Δ -0.45) | -0.49 to +0.17 (Δ +0.66) | dlr NEUTRAL to MODERATE SHORT; lev NEUTRAL (held) | flow z -2.64^, WoW -35,852; dealer 30.8th pctl, net +82,107 (long CAD, at the low end of its range); lev net -55,448 short CAD; AM z +0.64; top-4 58.6%; 4 straight weeks of dealer net decline |
| 13 | VIX | REGIME TRANSITION, PROTECTION DEMAND EASING | +0.41 to +0.56 (Δ +0.15) | +0.42 to +0.52 (Δ +0.10) | dlr NEUTRAL to MODERATE LONG; lev NEUTRAL to MODERATE LONG | dealer 69.2nd pctl, net +52,894 long VIX = low protection demand; AM net short vol (z -1.68) confirms the complacent read; small traders net long VIX z +1.47 at 93rd pctl, a crowded protection bid; 26% of lev gross in spread structure; OptZ=+0.00 |
| 14 | UST 30Y | LEV LONG-END LEAN, BOTH COVERING | -1.00 to -0.87 (Δ +0.13) | +1.13 to +1.37 (Δ +0.24) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 20.2nd pctl, net -251,880; lev 94.2nd pctl, still net short in absolute terms (-276,965), adding ~25,320/wk; AM z +0.26; Other Reportables z -2.32 at 1st pctl; top-4 34.8%; OptZ=+0.50 |
| 15 | Bitcoin | LEV CROWDED LONG, DEALER LONG AT RANGE LOW | -1.03 to -1.03 (Δ 0.00) | +1.41 to +1.32 (Δ -0.09) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 4.8th pctl, net +2,943 (structural long at its range low); lev 87.5th pctl on a net of -7,892, below zero in absolute terms; AM z -1.45; RV 0.91x (n=33); top-4 60.9% on a thin 10L/11S book |
| 16 | GBP | REGIME TRANSITION, LEV BACK TO FLAT | +0.48 to +0.62 (Δ +0.14) | +0.65 to +0.04 (Δ -0.61) | dlr NEUTRAL to MODERATE LONG; lev MODERATE LONG to NEUTRAL | dealer 69.2nd pctl, net +68,548 (long GBP); lev net +34,627, unwinding ~2,949/wk; AM -105,864 short GBP (z -0.91); top-4 43.4%; OptZ=-1.30 |
| 17 | EUR | LEV CROWDED SHORT (dollar-bull) | +0.64 to +0.68 (Δ +0.04) | -1.38 to -1.19 (Δ +0.19) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -261,454 (short euro, at the high end of its short range, not a long); lev 18.3rd pctl also short euro (-33,285), so both sit the same side; AM +250,678 holds the euro long; OptZ=-1.43 |
| 18 | CHF | LEV CROWDED SHORT DEEPENED | +0.54 to +0.96 (Δ +0.42) | -0.81 to -1.32 (Δ -0.51) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer 79.8th pctl, net +60,845 (long CHF), 9L/0S; lev 12.5th pctl, net -13,440; AM z +0.13; dealers hold 65.9% of gross-long OI here; OptZ=+0.50 |
| 19 | Silver | COMMERCIALS HIGH, MM SHORT | +1.19 to +1.07 (Δ -0.12) | -1.00 to -0.81 (Δ +0.19) | Commercials MODERATE LONG (held); Managed Money MODERATE SHORT (held) | Commercials 76.0th pctl, net -17,517 hedge; Managed Money 32.7th pctl, net +14,386 long; Swap Dealers z +0.65; small traders 25.4% of OI, the board’s largest retail footprint |
| 20 | Gold | QUIET, HEDGERS MID-RANGE | +0.90 to +0.92 (Δ +0.02) | +0.05 to +0.03 (Δ -0.02) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 72.1st pctl, net -28,275 hedge; Managed Money net +139,548 long at 60.6th pctl; Swap Dealers z -1.17; Other Reportables 39.3% of OI; OI WoW +167,468, a large open-interest build |
| 21 | WTI Crude | QUIET, HEDGERS NET LONG | +0.77 to +0.75 (Δ -0.02) | +0.11 to +0.41 (Δ +0.30) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 79.8th pctl, net +308,916 (unusually net long for this cohort); Managed Money net +111,731, adding ~8,302/wk; Swap Dealers z -0.52; deepest commodity trader book on the board (61L/55S) |
| 22 | AUD | LEV CROWDED LONG, BOTH ADDING | -0.68 to -0.52 (Δ +0.16) | +1.29 to +1.26 (Δ -0.03) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 26.0th pctl, net -33,579 (short AUD); lev 86.5th pctl, net +49,779 long AUD; AM z -0.42; top-4 55.5%; OptZ=+0.16 |
| 23 | Natural Gas | SWAP DEALER EXTREME, REST QUIET | +0.25 to +0.31 (Δ +0.06) | -0.73 to -0.85 (Δ -0.12) | Commercials NEUTRAL (held); Managed Money MODERATE SHORT (held) | Swap Dealers z +2.17 at 99th pctl, net +216,391; Commercials 63.5th pctl, net -15,265; Managed Money net -96,742 short, aligned with the hedge; Other Reportables z -0.80 |
| 24 | Ether | QUIET, FLOW WITHOUT LEVEL | -0.22 to +0.26 (Δ +0.48) | +0.81 to +0.42 (Δ -0.39) | dlr NEUTRAL (held); lev MODERATE LONG to NEUTRAL | flow z +1.74^, WoW +2,045 on a neutral base; dealer 60.6th pctl, net +9,403 (structural long); AM z -1.33; top-4 80.0% on a thin 4L/10S book, the board’s most concentrated; OptZ=-0.54 |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
The curve is the only place on the board where both sides of the book are stretched at once, and this week the stress migrated outward rather than releasing. The front end is where the crowding lives: leveraged funds hold the top of their own range across 2Y, 5Y and 30Y while dealers sit below theirs, and the SOFR contract carries both cohorts at outright extremes simultaneously. Read that as maximum counterparty tension into the Fed rather than as conviction about the level of rates; in every one of those books the leveraged position is still net short in absolute terms, so a “crowded long” here means crowded relative to their own history, not an outright bullish duration bet.
Two caveats travel with the rates complex unchanged from last week and they still bind. First, the leveraged spread share in SOFR is large enough that the directional read overstates conviction; the same basis and calendar-spread flow that produces a dealer footprint at the extremes produces no directional view at all. Second, the options-implied dealer delta in SOFR is not stretched, so the futures extreme there reads as a basis or directional footprint and the options-hedging hypothesis has no support. The 10Y is the exception on both counts: its options-implied delta is stretched the same way the futures book is, which is the only place this week where the gamma hypothesis has corroboration rather than a caveat, and even there the measured realized-vol ratio shows no amplification. The 5Y is the tenor to watch for the standoff resolving, because dealers and leveraged funds are both extending in the same direction there, which compresses the counterparty tension that normally drives sharp unwinds.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
The dollar story is coherent and it has not changed shape. The buy-side holds the Dollar Index long while running short the euro through the leveraged book, and dealers absorb the other side at a stretched short in DXY; those three facts tell one consistent bullish-dollar positioning story rather than three separate ones. The Dollar Index is also the board’s highest measured realized-vol ratio, and the ledger behind it is thin and one-sided enough that the concentration flag matters more than the z-score: a handful of traders carry the dominant side. Prior ELEVATED SHORT episodes in the Dollar Index ran a median 4-week return of -0.3% with 0 of 5 bullish, against an unconditional baseline of +0.1% median and 52% bullish across all weeks (n=885). Five episodes is not a sample to lean on; treat the skew as historical context, not a forecast.
The yen was the week’s real FX event. The repositioning was the largest relative flow anywhere on the board and it moved both cohorts at once: dealers crossed the zero line and leveraged funds abandoned an elevated short back to flat. That is a structural reset of the book rather than a directional statement, and with the Bank of Japan on the calendar chatter alongside the Fed, it leaves the yen with the least stale positioning of any major. The Canadian dollar produced a smaller version of the same thing, a regime crossing on outsized flow into a fourth straight week of dealer net decline. The peso stays the second opposed-extremes book, with leveraged funds actively extending a crowded long against a dealer short that keeps eroding, and its prior episodes carry a mild positive skew versus baseline that the sample size does not support leaning on. Sterling and the franc both cleared the gate on cohort crossings without level: leveraged funds released a long in sterling and deepened a short in the franc, neither from a stretched base. The Australian dollar sits quiet with both cohorts leaning the same way.
Equities (S&P 500, Nasdaq, Russell 2000)
Equity positioning normalized in both directions this week. S&P dealers crossed up out of neutral on outsized flow with no calendar catalyst behind it, while Nasdaq dealers crossed back down into neutral from the short side; the two indices are now moving toward each other rather than apart, which drains the sector-rotation divergence that has been the equity read for several weeks. The one figure that still separates them is the Nasdaq options-implied dealer delta, which is the most stretched on the board and sits well short of where the futures book reads, so the tech extreme this week is an options-book fact rather than a futures-positioning fact.
The Russell remains the group’s genuine tension and it is the standing story rather than the new one. Leveraged funds hold an extreme short against an outright dealer long that carries the equity complex’s concentration flag, and they are still reducing into it, which is the textbook squeeze-fuel configuration: a crowded short that is being extended has more to unwind if a catalyst forces it. Prior MODERATE LONG DELTA episodes in the Russell returned a median +5.8% over 4 weeks with 4 of 5 bullish, against an unconditional baseline of +1.1% median and 60% bullish (n=475). That is a deviation worth noting, but five episodes is context, not a signal, and the forward window is anchored to Tuesday, so three sessions of it have already elapsed. Small traders sit at a crowded extreme in the Nasdaq book, the classic contrarian-watched posture, and that is convention rather than a forecast.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Copper is the only commodity that cleared the gate and it cleared it on all three counts: a regime step, the group’s largest flow, and a full opposed-extremes configuration with Commercials stepping deeper into their hedge while Managed Money extends a speculative long, on a concentrated book. The Commercials-versus-Managed-Money gap is the canonical hedger-versus-speculator read here, and describing the tension is where it ends. There is no measured forward-return edge in this market; prior ELEVATED SHORT episodes for Commercials ran a median 4-week return of -1.4% with 2 of 5 bullish against an unconditional baseline of +0.8% median and 55% bullish (n=885), which is well inside noise for a five-episode sample. Other Reportables also sit near the top of their range in copper, so the long side of the hedge is spread across more than just the speculative crowd.
The rest of the complex sat quiet. Gold and silver hedgers hold the same mid-to-high posture as last week with the speculative crowd flat to slightly short, crude’s Commercials remain unusually net long for that cohort with the deepest trader participation on the board, and natural gas is a Swap Dealer story rather than a hedger-versus-speculator one, with Commercials and Managed Money leaning the same way.
Crypto (Bitcoin, Ether)
The intra-crypto split widened and it is a divergence in posture, not in direction. Ether dealers crossed back toward the middle of their range while Bitcoin dealers held at the bottom of theirs, so the structural dealer long in Bitcoin sits at the low end of its two-year range while Ether’s sits comfortably mid-range. That is the rotation the board has been signaling for two weeks, and the standing caveat still applies unchanged: crypto dealers are structurally net long, so a negative z-score here is a compressed long, never a literal short. Leveraged funds run the counterparty side in both, crowded long in Bitcoin relative to their own range while still net short in absolute terms, which is the same arithmetic trap as the rates book. Ether’s flow cleared the notable threshold on a neutral base, so it stays a table row rather than a story, and both books are thin enough at the top that the concentration numbers deserve more weight than the z-scores. Bitcoin’s prior MODERATE SHORT DELTA episodes returned a median +8.5% over 4 weeks with 3 of 5 bullish against an unconditional baseline of +2.1% median and 57% bullish (n=622); with five episodes and a wide dispersion that is context, not conviction. Bitcoin positioning stress is also decoupled from the equity complex this week, so do not read it as part of a broad risk-off.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (Consol) | 6,620.09 – 6,820.20 | 7,666.75 | above zone | 7,095.91 – 7,315.31 | above zone |
| Nasdaq (Consol) | 29,034.65 – 29,979.65 | 29,417.75 | inside zone | 28,376.65 – 29,432.92 | inside zone |
| Russell 2000 | 2,825.62 – 2,924.76 | 2,907.20 | inside zone | 2,854.08 – 2,951.17 | inside zone |
| VIX | 15.72 – 19.06 | 15.85 | inside zone | 14.30 – 16.03 | inside zone |
| USD Index | 99.49 – 100.94 | 99.12 | below zone | 99.13 – 99.93 | below zone |
| Bitcoin | 76,578.33 – 83,105.04 | 77,234.54 | inside zone | 72,571.70 – 78,932.08 | inside zone |
| Ether | 2,262.12 – 2,494.07 | 2,539.41 | above zone | 2,198.50 – 2,406.76 | above zone |
| Gold | 4,148.79 – 4,331.37 | 4,389.50 | above zone | 3,968.76 – 4,150.55 | above zone |
| Silver | 57.63 – 63.75 | 64.90 | above zone | 65.02 – 72.12 | below zone |
| WTI Crude | 77.61 – 91.70 | 100.57 | above zone | 80.91 – 93.37 | above zone |
| Copper | 5.71 – 5.97 | 6.55 | above zone | 5.84 – 6.11 | above zone |
| Natural Gas | 2.84 – 3.10 | 2.83 | below zone | 2.78 – 3.01 | inside zone |
Rates are excluded from cost basis by construction: structural shorts that never cross zero make the estimate unreliable. Four books trade inside their dealer zone this week (Nasdaq, Russell, VIX, Bitcoin), meaning the aggregate epoch position sits near flat P&L; the Dollar Index and natural gas trade below both zones and the commodity and large-cap equity books trade above. This is a descriptive P&L fact about the aggregate book. Tested in 2026, no covering response follows from a basis crossing, so do not treat any of these as triggers.
BOTTOM LINE
The risk into the Fed is concentrated in the front end, not in equities: size positions against a rates complex where leveraged funds and dealers are simultaneously at the top and bottom of their own ranges, and discount the crowding half of that read by the spread-structure share and the options caveat before acting on it. Everything else on the board, equities included, is normalizing toward the middle.
Data: CFTC COT Report 2026-09-08 | Prices as of 2026-09-11 | Analysis window: 104 weeks
Smart Money Pulse - '26 W36
The Most Lopsided Bet on the Board Is Now in Small Caps
For much of the past month the crowded corners of this data sat in bonds and the dollar. The sharpest one-sided book in the report now sits in small caps, where the professional desks hold a genuine outright long near the very top of their two-year range while the hedge fund crowd has pressed a short to the bottom of its own, the most lopsided speculative position on the board.
That matters more to an ordinary portfolio than it sounds. Small caps are the sleeve most people own without thinking about it, through IWM or the small-company slice inside a total-market index fund, and this is the one equity book where a handful of large desks control most of the dominant side. A thin, one-sided book is a condition, not a forecast. It says nothing about which way things go and quite a lot about how fast the market could move if something knocks it.
The calendar is dense from here. August payrolls landed Friday morning at 162,000 jobs, more than double what economists expected; CPI, the monthly consumer inflation reading, follows on September 9, and the Federal Reserve’s rate decision comes September 17. Keep in mind this is Tuesday’s picture. Small caps have already climbed since then and the fear gauge slid toward the mid-14s, but none of that turns up in the positioning data until next week’s report.
This Week's Positioning
Small caps: the two big cohorts are as far apart as the data goes
Dealers hold an outright net long in Russell 2000 futures sitting at the 98th percentile of its two-year range, and the hedge fund crowd answered by driving its short to the extreme low end of its own (z=-2.07). The dealer side carries the only equity concentration flag on the board, meaning a small number of desks own most of that position, so there is not much depth behind it if either side has to move.
Watch: how IWM trades around the September 9 inflation print. That is the first real test of a book with almost nobody sitting on the other side.
Treasuries: the bet that defined last week already came apart
The 5-Year Treasury short that was the single deepest position anywhere on the board a week ago snapped back two full steps, on the largest weekly repositioning in the rate complex, while the 10-Year went the opposite direction and is now the most stretched dealer short in the report (z=-2.03, the very bottom of its two-year range). The professional desks also hold an enormous outright long in SOFR futures, the market’s bet on short-term interest rates, near the high end of its range, with hedge funds jammed into the opposite corner.
Watch: whether longer-dated bond funds like TLT start behaving differently from short-dated ones like SHY through the September 17 Fed decision. The positioning stress has migrated from the middle of the curve out to the long maturities.
Nasdaq: the pros and the fast money traded places
Dealers crossed out of neutral and into a moderate short in a single week (z=-0.61) while the hedge fund crowd moved the other way, up to the high end of its own range (z=+0.82), on repositioning the tool flags as unusually large with no scheduled event behind it. Neither side is stretched yet, but two cohorts crossing in opposite directions inside one week is how a crowded trade starts to build.
Watch: QQQ into the September 9 inflation reading. If the two sides keep separating, this becomes next month’s crowded book rather than this month’s footnote.
The Japanese yen: the speculative short got deeper
Hedge funds pushed their yen short down to the low end of its two-year range (z=-1.73), while dealers went the other way and now hold a genuine net long in the yen, one of the biggest weekly shifts in the entire currency book. Since Tuesday’s snapshot the yen has strengthened against the dollar, which is price action and not evidence that anybody has covered anything.
Watch: the dollar-yen exchange rate. A continued yen rally leans on one of the more one-sided currency positions in this report, and Japan-heavy international funds are where a regular investor feels it.
Everything else is either standing still or standing pat. The dollar index is still the report’s most durable stretch, with dealers pinned short against a fast-money long, but it barely moved a contract this week, and the Mexican peso holds the same maximum-tension setup it has carried for weeks. Dealer positioning in the fear gauge eased back to neutral and the big asset managers showed little appetite for protection, though small traders, the crowd your own account belongs to, are the ones buying protection near the top of their range, and that is often where the crowd gets it wrong. Bitcoin’s professional long keeps thinning toward the floor of its range while hedge funds sit near the top of theirs, the euro, British pound, Canadian dollar and Australian dollar all sat quiet, the Swiss franc drifted into a mild dealer long, and gold, silver, copper, crude and natural gas show the usual gap between hedgers and speculators with nothing at a genuine extreme.
Know Where You Stand
- Find out how much small-cap exposure you are actually carrying. Plenty of people hold more than they realize through a total-market fund or a target-date fund’s equity sleeve rather than through IWM directly, and this is the week the data says that slice sits on the thinnest, most one-sided book in the report; the point is to size it deliberately, not to trade it.
- Your bond holdings are not one thing, and the pressure just moved along the curve. Short-dated funds like SHY and long-dated ones like TLT are answering to different crowds right now, and a broad fund like BND blends both, so if you own bonds through a single ticker it is worth knowing which end of the maturity range you are really exposed to before September 17.
- Two dates own the next two weeks, so set a rebalance date rather than reacting to each print. CPI on September 9 and the Fed decision on September 17 both land on the same crowded rate and currency books, and a 60/40 or target-date investor is exposed to them through the stock sleeve and the bond sleeve at once; picking a single date after the 17th to review your allocation beats making two separate decisions under a headline.
Data: CFTC COT Report 2026-09-01 | Prices as of 2026-09-04 | 104-week lookback
Liquidity Trajectory '26 W36
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-09-01 | Generated: 2026-09-04 16:00 ET
EXECUTIVE SUMMARY
- The rates curve stayed the board’s stress center, but the pressure moved. The UST 5Y released two tiers, dealers from EXTREME SHORT to MODERATE SHORT (z -2.19 to -1.12) on the largest rate-book repositioning of the week (flow z +2.65^, WoW +114,590 contracts), while the 10Y held its EXTREME SHORT at the 0.0th percentile (z -2.03). Measured asset managers sit long the 10Y at the 98th percentile (AM z +1.82). Measured realized vol in the 10Y’s regime runs 1.03x the all-week average (n=57), so the short-gamma amplification story is not evident in this market’s history.
- SOFR 3M remains the single OPPOSED EXTREMES book at the policy-sensitive front end. Dealers hold an outright +3,379,318 contract long at the 98.1st percentile against a leveraged fund short at the 4.8th percentile, with measured asset managers washed out at the 0th percentile (AM z -2.05). The lev regime eased a tier (z -2.00 to -1.97), 39% of lev gross exposure there is spread structure, and the options-implied dealer delta carries a caveat (OptZ=-2.18), so read the futures extreme as a basis or directional footprint, not gamma.
- Equity positioning re-stretched in the small caps and rolled over in tech. Russell 2000 leveraged funds pushed from ELEVATED to EXTREME SHORT (z -2.07, 1.9th percentile) against an outright dealer long of +96,593 contracts at the 98.1st percentile carrying the board’s equity concentration flag (30L/20S #). Nasdaq dealers crossed from NEUTRAL into MODERATE SHORT on outsized flow (Consol flow z -2.20^) while leveraged funds crossed the other way. Group equity dealer average is +0.34z.
- The dollar book held its stretch, the peso kept maximum tension, and yen speculative shorts deepened. USD Index dealers stayed ELEVATED SHORT (z -1.92, 4.8th percentile) on a heavily concentrated ledger (7L/0S #) with measured realized vol at 1.19x the all-week average (n=34), the one amplified-vol reading on the board. MXN is the second OPPOSED EXTREMES book (dealer z -1.81 against lev z +1.64), and JPY leveraged funds moved from MODERATE to ELEVATED SHORT (z -1.73, 1st percentile) on unusually large dealer flow (flow z +2.10^). VIX and Ether both transitioned to NEUTRAL dealer regimes, Ether on the board’s largest relative flow (flow z -3.43^).
- Catalyst line: August payrolls printed this morning at 162,000, more than double expectations, hitting the crowded front-end rate books and the stretched dollar ledger first. CPI follows Sep 9, five days out, and the FOMC decision Sep 17, thirteen days out; both land on the same SOFR, 2Y and USD Index books. PCE sits outside the two-week window on Sep 25.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-09-01 Tuesday snapshot; the price moves below are current through Friday September 4 and run on a different clock. Price action does not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | +1.05% | ES=F ~7,723 |
| Nasdaq | +1.45% | NQ=F ~29,547 |
| Russell 2000 | +1.78% | RTY=F ~2,977 |
| VIX | -12.79% | ^VIX 14.25 |
| Bitcoin | +3.06% | ~79,774 |
| Ether | +1.63% | ~2,457 |
| UST 10Y | -0.12% | ZN=F futures down = yields up |
| UST 5Y | -0.09% | ZF=F futures down = yields up |
| UST 2Y | -0.11% | ZT=F futures down = front-end yields up |
| Dollar Index | -0.53% | DX-Y.NYB 99.14, USD down |
| JPY | +2.50% | 6J=F up = yen up vs dollar |
| Copper | +2.41% | HG=F 6.66 |
The August jobs report landed this morning and beat expectations by a wide margin, and the immediate tape read as a Fed repricing: front-end and long-end futures both slipped, equities and small caps firmed, the fear gauge dropped to the mid-14s and the dollar index eased despite the strong print, with the president publicly pressuring the Fed to cut. Crypto whipsawed around the release before finishing higher on ETF inflows. All of this is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund or asset manager repositioning. The next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | SOFR 3M | OPPOSED EXTREMES | +2.25 to +2.43 (Δ +0.18) | -2.00 to -1.97 (Δ +0.03) | dlr EXTREME LONG (held); lev EXTREME to ELEVATED SHORT | dealer 98.1st pctl, net +3,379,318, WoW +268,187; lev 4.8th pctl; AM z -2.05 at 0th pctl; 39% lev gross in spread structure; OptZ=-2.18 caveat; top-4 94L/91S # |
| 2 | UST 10Y | DEALER EXTREME SHORT, STANDING | -2.04 to -2.03 (Δ +0.01) | -0.52 to -0.26 (Δ +0.26) | dlr EXTREME SHORT (held); lev MODERATE SHORT to NEUTRAL | dealer 0.0th pctl, net -587,097; AM long 98th pctl (z +1.82); RV 1.03x (n=57), no amplification; OptZ=-0.88; 4 straight weeks of dealer net decline |
| 3 | UST 2Y | LEV EXTREME LONG, REAL MONEY WASHED OUT | -1.31 to -1.11 (Δ +0.20) | +2.91 to +2.66 (Δ -0.25) | dlr MODERATE SHORT (held); lev EXTREME LONG (held) | lev funds 97.1st pctl, still net short in absolute terms (-1,268,034), adding ~28,471/wk; AM z -2.38 at 0th pctl; small traders z -1.79, washed out; OptZ=-0.76 |
| 4 | Russell 2000 | LEV CROWDED SHORT DEEPENED + CONCENTRATION # | +1.24 to +1.39 (Δ +0.15) | -1.68 to -2.07 (Δ -0.39) | dlr MODERATE LONG (held); lev ELEVATED to EXTREME SHORT | dealer 98.1st pctl, outright long +96,593, top-4 30L/20S #; lev 1.9th pctl; AM z -0.58; RV 0.95x (n=100); OptZ=-0.30 |
| 5 | UST 5Y | REGIME RELEASE, TWO TIERS | -2.19 to -1.12 (Δ +1.07) | +1.99 to +1.74 (Δ -0.25) | dlr EXTREME to MODERATE SHORT; lev ELEVATED LONG (held) | flow z +2.65^, WoW +114,590, the largest rate-book repositioning this week; dealer 12.5th pctl; lev 89.4th pctl unwinding ~10,683/wk, thin lev book 61L/78S #; AM z -0.84; OptZ=-0.78 |
| 6 | Nasdaq (Consol) | REGIME TRANSITION, BOTH COHORTS CROSSED | -0.11 to -0.61 (Δ -0.50) | -0.26 to +0.82 (Δ +1.08) | dlr NEUTRAL to MODERATE SHORT; lev NEUTRAL to MODERATE LONG | flow z -2.20^, WoW -15,039; dealer 31.7th pctl; lev 73.1st pctl adding ~25,947/wk; AM z +0.32; OptZ=-1.47; Mini dlr -0.27 to -0.80 (Δ -0.53), small traders z +1.45 at 94th pctl |
| 7 | USD Index | DEALER STRETCHED SHORT + CONCENTRATION # | -1.95 to -1.92 (Δ +0.03) | +1.25 to +1.10 (Δ -0.15) | dlr ELEVATED SHORT (held); lev MODERATE LONG (held) | dealer 4.8th pctl, net -27,015; buy-side long DXY (lev +7,133, AM z +1.11) = bullish USD; MEASURED VOL 1.19x (n=34); OptZ=+0.00 caveat; top-4 74.9%, 7L/0S # |
| 8 | MXN | OPPOSED EXTREMES | -1.76 to -1.81 (Δ -0.05) | +1.50 to +1.64 (Δ +0.14) | dlr ELEVATED SHORT (held); lev MODERATE to ELEVATED LONG | dealer 3.8th pctl, net -124,691 (short peso); lev 97.1st pctl long peso, unwinding ~219/wk; AM z +1.21; RV 0.97x (n=37), no amplification; OptZ=+0.60 caveat; 4 straight weeks of dealer net decline |
| 9 | JPY | LEV SHORT DEEPENED ON OUTSIZED FLOW | +1.01 to +1.33 (Δ +0.32) | -1.09 to -1.73 (Δ -0.64) | dlr MODERATE LONG (held); lev MODERATE to ELEVATED SHORT | flow z +2.10^, WoW +36,383; dealer 90.4th pctl, net +79,321 (long yen); lev 1.0th pctl short yen; AM z -0.94; OptZ=+0.07 |
| 10 | VIX | REGIME TRANSITION to NEUTRAL, PROTECTION EASING | +0.53 to +0.41 (Δ -0.12) | +0.28 to +0.42 (Δ +0.14) | dlr MODERATE LONG to NEUTRAL; lev NEUTRAL (held) | dealer 63.5th pctl, net +48,862 long VIX = low protection demand; AM net short vol (z -1.42) confirms the complacent read; small traders net long VIX z +1.57 at 94th pctl, crowded protection bid; OptZ=+0.00 |
| 11 | Ether | REGIME TRANSITION on BOARD-LARGEST FLOW | +0.72 to -0.22 (Δ -0.94) | +0.17 to +0.81 (Δ +0.64) | dlr MODERATE LONG to NEUTRAL; lev NEUTRAL to MODERATE LONG | flow z -3.43^, WoW -3,872; dealer 35.6th pctl, net +7,358 (structural long); AM z -1.27; top-4 78.7% on a thin 5L/9S book; OptZ=-0.53 |
| 12 | Bitcoin | LEV CROWDED LONG, DEALER LONG THINNING | -0.73 to -1.03 (Δ -0.30) | +1.34 to +1.41 (Δ +0.07) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 4.8th pctl, net +2,784 (structural long at its range low); lev funds 88.5th pctl on a net of -7,620 contracts, below zero in absolute terms; AM z -1.40; RV 0.89x (n=32); top-4 61.7% on a thin 10L/10S book |
| 13 | Copper | COMMERCIALS vs MANAGED MONEY | -1.34 to -1.23 (Δ +0.11) | +1.59 to +1.41 (Δ -0.18) | Commercials MODERATE SHORT (held); Managed Money now MODERATE LONG (was ELEVATED) | Commercials 12.5th pctl, net -96,827 hedge; Managed Money 90.4th pctl, net +73,000 long; Swap Dealers z -1.74 at 1st pctl; Other Reportables z +1.26 |
| 14 | UST 30Y | LEV LONG-END LEAN | -1.14 to -1.00 (Δ +0.14) | +1.15 to +1.13 (Δ -0.02) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 18.3rd pctl; lev 86.5th pctl adding ~24,373/wk; AM long z +0.47; Other Reportables z -2.48 at 0th pctl; top-4 35.7%; OptZ=-0.19 |
| 15 | EUR | LEV CROWDED SHORT (dollar-bull) | +0.64 to +0.64 (Δ 0.00) | -1.41 to -1.38 (Δ +0.03) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -267,578 (short euro, high end of its short range, not a long); lev 14.4th pctl short euro; AM +263,253 holds the euro long; OptZ=-1.52 |
| 16 | AUD | LEV CROWDED LONG | -0.60 to -0.68 (Δ -0.08) | +1.45 to +1.29 (Δ -0.16) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 20.2nd pctl, net -43,456 (short AUD); lev 86.5th pctl, net +49,662 long AUD; AM z -0.11; top-4 62.6%; OptZ=-0.34 |
| 17 | S&P 500 (Consol) | STANDOFF, OUTSIZED FLOW AT NEUTRAL | -0.16 to +0.23 (Δ +0.39) | +0.30 to +0.23 (Δ -0.07) | dlr NEUTRAL (held); lev NEUTRAL (held) | flow z +1.82^, WoW +43,258 without a calendar catalyst; dealer 53.8th pctl, net -701,233 (short in absolute terms); AM z -0.07; OptZ=-0.29; E-Mini dlr -0.30 to +0.08 (Δ +0.38) |
| 18 | Silver | COMMERCIALS HIGH, MM SHORT | +1.17 to +1.19 (Δ +0.02) | -0.93 to -1.00 (Δ -0.07) | Commercials MODERATE LONG (held); MM MODERATE SHORT (held) | Commercials 79.8th pctl, net -16,677 hedge; Managed Money 26.0th pctl, net +12,170 long; Swap Dealers z +0.63; small traders 23.7% of OI |
| 19 | CHF | REGIME TRANSITION + OPTIONS-IMPLIED LONG | -0.03 to +0.54 (Δ +0.57) | -0.57 to -0.81 (Δ -0.24) | dlr NEUTRAL to MODERATE LONG; lev MODERATE SHORT (held) | dealer 67.3rd pctl, net +55,743 (long CHF); OptZ=+1.51, options-implied dealer delta stretched long; lev 21.2nd pctl; AM z +0.52 |
| 20 | Gold | QUIET, HEDGERS MID-RANGE | +0.76 to +0.90 (Δ +0.14) | +0.32 to +0.05 (Δ -0.27) | Commercials MODERATE LONG (held); MM NEUTRAL (held) | Commercials 72.1st pctl, net -28,962 hedge; Managed Money net +140,811 long at 59.6th pctl; Swap Dealers z -1.03; Other Reportables 38.2% of OI |
| 21 | WTI Crude | QUIET, HEDGERS NET LONG | +0.95 to +0.77 (Δ -0.18) | +0.28 to +0.11 (Δ -0.17) | Commercials MODERATE LONG (held); MM NEUTRAL (held) | Commercials 80.8th pctl, net +309,402 (unusually net long for this cohort); Managed Money net +94,281; Swap Dealers z -0.40; deepest trader book on the board (58L/55S) |
| 22 | Natural Gas | SWAP DEALER EXTREME, REST QUIET | +0.19 to +0.25 (Δ +0.06) | -0.42 to -0.73 (Δ -0.31) | Commercials NEUTRAL (held); Managed Money now MODERATE SHORT (was NEUTRAL) | Swap Dealers z +2.04 at 99th pctl, net +210,225; Commercials 60.6th pctl, net -16,961; Managed Money net -89,523 short, aligned with the hedge |
| 23 | GBP | QUIET | +0.31 to +0.48 (Δ +0.17) | +0.97 to +0.65 (Δ -0.32) | dlr NEUTRAL (held); lev MODERATE LONG (held) | dealer 67.3rd pctl, net +59,203 (long GBP); lev 76.9th pctl, net +43,167 long GBP; AM z -0.96; top-4 47.3%; OptZ=-0.94 |
| 24 | CAD | QUIET | +0.05 to -0.05 (Δ -0.10) | -0.66 to -0.49 (Δ +0.17) | dlr NEUTRAL (held); lev MODERATE to NEUTRAL SHORT | dealer 51.0th pctl, net +117,959 (long CAD); lev 32.7th pctl, net -68,750 short CAD; AM z +0.32; top-4 55.8%; OptZ=+0.17 |
POSITIONING DYNAMICS
Equities (S&P 500, Nasdaq, Russell 2000)
The equity board split cleanly this week. Russell 2000 is now the sharpest one-sided book on the equity board: dealers hold an outright long near the top of their two-year range while leveraged funds pressed their short a full tier deeper into extreme territory, and the dealer side carries the only equity concentration flag, meaning that book is thin if it has to turn. That configuration is textbook squeeze fuel on the lev side, though it is market structure, not a directional call. Nasdaq did the opposite: both cohorts crossed the neutral boundary in opposite directions in a single week, dealers into a moderate short and leveraged funds into a moderate long, on flow the tool reads as unusually large without a calendar catalyst. Neither side is stretched yet, but the trend is divergent and it is the setup that builds a crowded trade if it extends. Note that Nasdaq small traders sit near the high end of their own range, the classic crowded contrarian posture, context only. S&P 500 is the quiet counterweight: dealers repositioned hard in contract terms yet ended the week sitting on their historical mean against a leveraged fund book doing the same, so the flow was large and the level says nothing. Dealers remain net short S&P 500 and Nasdaq in absolute terms throughout; the positive Russell reading is a genuine outright long.
Russell carries analog data. Five prior MODERATE LONG DELTA episodes returned a median +6.0% over the four weeks that followed, 4 of 5 bullish, against an unconditional base rate of +1.2% median and 59% bullish across all 474 weeks. The median runs well above the base rate and the hit rate edges it, but on five overlapping episodes this is historical context, not a signal, and the window is anchored to Tuesday, so three sessions of any such window have already elapsed.
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
Read the complex as one curve, not five tenors. The front end still holds the maximum-tension book: SOFR dealers pinned at the high end of their range against leveraged funds crowded at the opposite end is the only true opposed-extremes pair in rates, and the 2Y mirrors the counterparty logic with leveraged funds at the top of their own range against measured asset managers washed out at their floor. Two standing caveats carry over unchanged and neither has softened: a large share of leveraged gross exposure in SOFR sits in spread and roll structures, so the directional read there overstates conviction, and the options-implied dealer delta does not corroborate the futures extreme, which makes it a basis or directional footprint rather than an options-hedging story.
The long end is where the level sits. The 10Y dealer short is the deepest reading on the board and has now run four consecutive weeks lower, with measured asset managers holding the mirror duration long near the top of their range. The measured realized vol for that regime shows no amplification, so the short-gamma inference stays a hypothesis and nothing more. The 5Y is the week’s actual news: the deepest dealer short of last week released two full tiers on the largest rate-book repositioning of the week, while the leveraged fund long there began unwinding. That is the front-to-back-end pressure gradient reversing shape, not resolving. The 30Y adds a leveraged fund lean toward the top of its range and an Other Reportables book pinned at its floor, a completeness detail rather than the story.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
The dollar story stays coherent and it belongs to the leveraged funds. They hold the dollar index long alongside asset managers while dealers sit stretched short the index, and the mirror shows up cleanly in the low yielders: leveraged funds are short euro, short yen at the low end of their yen range and short franc. Mind the sign discipline in the euro, where dealers read as a moderate long regime yet remain short the contract, sitting near the high end of their short range, so dealers and leveraged funds are on the same side there and the euro long belongs to asset managers. The yen is the one FX book that moved with force this week, dealer flow the tool flags as unusually large while the speculative short deepened a tier. The USD Index book also carries the only measured realized vol reading on the board that is consistent with amplification, alongside its options caveat, and its dealer ledger carries a concentration flag on an unusually thin book.
The peso is the second maximum-tension book, dealers stretched short against leveraged funds and asset managers both long, with the dealer net falling four straight weeks. Its options caveat and measured vol both argue against reading it as an options-hedging signal. The franc crossed into a moderate dealer long, the only other FX regime change, and it is the one currency where the options-implied dealer delta is itself stretched long. Sterling, the Australian dollar and the Canadian dollar sat quiet, the Australian dollar carrying a leveraged long against a dealer short that is crowded but not stretched.
The dollar index carries analog data. Five prior ELEVATED SHORT DELTA episodes returned a median -0.3% over the following four weeks with 0 of 5 bullish, against an unconditional base rate of +0.1% median and 52% bullish across all 885 weeks. The direction is one-sided against a coin-flip base rate, which is the one analog set this week that deviates meaningfully, but five episodes is five episodes; treat it as historical context only.
Crypto (Bitcoin, Ether)
Crypto dealers run structural longs, so both negative dealer readings mark the low end of a long range and not a literal short. Bitcoin’s dealer long thinned toward the floor of that range while leveraged funds held near the top of theirs, which the tool labels a crowded long even though the leveraged book is net short in absolute terms; read the label as range position, not direction. Ether was the board’s largest relative repositioning, dropping its dealer regime to neutral in one week while its leveraged book crossed the other way, and the dealer read there is now firmer than Bitcoin’s, which the narrative flags as possible intra-crypto rotation. Both crypto books are thinly held with a handful of traders controlling most of the dominant side, so the dealer signal in each carries that structural caveat. The narrative also notes Bitcoin stress is not mirrored in equity positioning, so this is crypto-specific and not a broad risk-off read.
Bitcoin’s analogs: five prior MODERATE SHORT DELTA episodes returned a median +8.5% over four weeks with 3 of 5 bullish, against a base rate of +2.1% median and 57% bullish across 621 weeks. The median runs above baseline while the hit rate does not; on five episodes it is context only.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Copper holds the only live hedger-versus-speculator tension: Commercials sit near the low end of their two-year range while Managed Money holds a large long that eased a tier this week, the canonical opposed configuration, and the Swap Dealer book sits at its own floor. This is positioning state, nothing more. Gold and silver Commercials both sit moderately high in their hedging ranges with Managed Money split, gold’s speculative book neutral and silver’s leaning short, so neither metal shows a stretch worth a headline. WTI Commercials are unusually net long for a cohort that normally carries a structural short, sitting high in their range on a deep and broadly held trader book. Natural gas is quiet on both the hedger and the speculative side; its only notable reading is the Swap Dealer book pinned near the top of its range, which is context, not a story.
COST BASIS LEVELS
Descriptive P&L facts about the aggregate book, not triggers; 2026 testing found no covering response after price crosses a cohort basis. Prices as of 2026-09-04.
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (Consol) | 6,622 – 6,824 | 7,722 | above zone | 7,063 – 7,288 | above zone |
| Nasdaq (Consol) | – | 29,543 | – | 27,679 – 29,092 | above zone |
| Russell 2000 | 2,825 – 2,926 | 2,976 | above zone | 2,855 – 2,952 | above zone |
| VIX | 15.78 – 19.14 | 14.26 | below zone | 14.30 – 16.03 | just below zone |
| USD Index | 99.49 – 100.94 | 99.14 | below zone | 99.13 – 99.93 | inside zone, at the low edge |
| Bitcoin | 76,584 – 83,258 | 79,727 | inside zone, mid | 72,433 – 78,879 | above zone |
| Ether | 2,222 – 2,454 | 2,456 | just above zone | 2,122 – 2,321 | above zone |
| Gold | 4,149 – 4,331 | 4,482 | above zone | 3,961 – 4,145 | above zone |
| Silver | 57.35 – 63.52 | 66.85 | above zone | 65.28 – 72.69 | inside zone, low end |
| WTI Crude | 77.61 – 91.70 | 91.33 | inside zone, top | 79.07 – 91.31 | just above zone |
| Copper | 5.60 – 5.85 | 6.66 | above zone | 5.76 – 6.02 | above zone |
| Natural Gas | 2.84 – 3.10 | 2.94 | inside zone, mid | 2.78 – 3.01 | inside zone, upper |
Commodity rows read as Commercials (dealer columns) and Managed Money (lev columns). Rates are excluded from cost basis by construction. Most equity and commodity books trade above both cohort zones; the VIX and dollar index dealer books are the two trading through from below.
BOTTOM LINE
Size rate and dollar risk off the front end this week, not the long end: the 5Y released and the 10Y did not, so the curve’s positioning gradient has flipped shape into CPI and the FOMC, and the SOFR and 2Y books remain the ones a surprise would force. In equities, Russell 2000 is the only book where a catalyst meets genuinely thin, one-sided inventory on both cohorts, so treat small-cap exposure as the position most sensitive to a squeeze if the tape turns.
Data: CFTC COT Report 2026-09-01 | Prices as of 2026-09-04 | Analysis window: 104 weeks

