Smart Money Pulse - '26 W42
The Bond Market’s Crowded Corner Moved to the 5-Year
As of Tuesday, Treasury positioning had found a new pressure point. Last week the 10-Year was the one maturity still pinned at an extreme; this week its dealers eased back a tier while dealers in the 5-Year Treasury added to their short at an unusually fast clip, landing near the bottom of their two-year range.
That matters if you own a core bond fund. The 5-Year sits in the middle of what BND or a short-to-intermediate Treasury fund like IEI holds, and the next two scheduled tests arrive back to back: the Fed’s rate decision (the FOMC meeting, October 28) and PCE (the Fed’s preferred inflation measure, October 29). It is also less of a two-sided fight than it sounds: the hedge fund crowd is short the 5-Year as well, so the other side of the dealer book belongs to asset managers, the pension and fund money that sits behind most retirement accounts.
This is Tuesday’s picture. Since then CPI (the consumer price index, the monthly inflation report) came out on Wednesday and stocks slid as headlines pointed to worries about the AI trade and higher oil prices; the Nasdaq fell about 4.6% while the S&P 500 lost about 2%. Treasuries rallied the other way, led by the 30-Year, which means yields fell; none of it shows how dealers handled the week, and next week’s report is the first that can.
This Week’s Positioning
The 5-Year Treasury: the stretch moved to the middle maturities
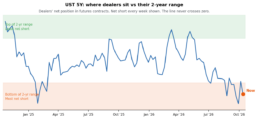
Dealers in the 5-Year went from a moderate short into stretched territory (z=-1.86) on a build far heavier than an options-expiration week typically brings. The 10-Year and 2-Year dealers both covered a tier at the same time, so the crowding concentrated in one maturity rather than spreading across the curve. Dealers’ options book in the 5-Year leans the opposite way, which fits hedging or arbitrage trades better than a straight bet on rates.
Watch: the Fed decision on October 28 and PCE the next day, the first scheduled numbers to land on the 5-Year’s new stretch.
The euro: the hedge fund bet against it reached a two-year extreme
The hedge fund crowd pressed its short in the euro to the very bottom of its two-year range (z=-2.15), while dealers are net short the euro too, so the two are on the same side and the big asset managers hold the long. With asset managers also long the dollar index, this is one story rather than two: the speculative money leans toward a firmer dollar, which is the setting that weighs on unhedged international funds. Since Tuesday the euro has actually edged up about half a percent and the dollar index slipped to about 101.8.
Watch: the euro between $1.13 and $1.14, the zone where the hedge fund crowd built its short and right where it trades now.
The Australian dollar: dealers stepped off neutral
Dealers moved from neutral into a moderate long on the Australian dollar, on a build unusually large for an options-expiration week. The hedge fund crowd is long as well, which leaves the big asset managers holding the short, and theirs is the deepest in their two-year range; in currencies that arrangement often reflects hedging rather than a view on direction. The Aussie has slipped about 0.7% against the dollar since Tuesday.
Watch: whether the Australian dollar gets back above 70 cents, the bottom of the zone where the hedge fund crowd built its long; it ended the week just under it, which matters if you hold an Australia fund like EWA.
Elsewhere: Bitcoin’s dealer long, which is structural, slid to the lowest reading in its two-year range, still a long and not a bet against it, with Bitcoin down about 2% since Tuesday to around $81,300. Dealers in the British pound hold a genuine long just shy of extreme, though their options book no longer backs it up, and SOFR futures (the market’s bet on short-term interest rates) kept their dealer stretch for another week. Mexican peso dealers extended a four-week build and the Swiss franc’s hedge fund short deepened without changing tier. The 30-Year’s hedge fund crowd held its extreme on paper, still short outright, and small-trader positioning in the 2-Year sits at the low end of its two-year range. In stocks the picture stays mild: S&P 500 dealers remain less short than usual, Nasdaq dealers added shorts for a second week and the Russell 2000 hedge fund short eased a tier, while institutions remain heavy sellers of volatility protection in the VIX market. In commodities, crude oil’s hedgers added heavily as oil climbed about 5% since Tuesday to near $99, natural gas hedgers drifted back to the middle of their range and gold, silver and copper were quiet.
Know Where You Stand
- Any hedge you add now costs more than it did on Tuesday, so price it at today’s level. On Tuesday institutions held a historically stretched bet against volatility with the VIX near 15; it has since climbed to about 20, so protecting an SPY or QQQ position is noticeably dearer, which describes cost, not where the market goes next.
- Check whether your bonds actually cushioned your stocks this week. Treasuries rallied while stocks fell after Tuesday, with long-dated funds like TLT moving the most, so pull up your own statement and see how much of the equity drop your BND, IEI or TLT holding offset.
- Put a dollar figure on what the Nasdaq’s slide did to your account. The Nasdaq fell more than twice as far as the S&P 500 since Tuesday, so if QQQ and the megacap names inside SPY make up a large share of your money, compare the actual loss to the drawdown you decided in advance you could live with.
Data: CFTC COT Report 2026-10-13 | Prices as of 2026-10-16 | 104-week lookback
Liquidity Trajectory '26 W42
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-10-13 | Generated: 2026-10-16 15:47
EXECUTIVE SUMMARY
- Treasury dealer short stress moved from the 10Y into the belly. UST 5Y dealers stepped MODERATE to ELEVATED SHORT on a WoW change of -82,152 contracts, an event z of -2.28 for a Monthly OpEx week and a flow z of -1.85, while UST 10Y dealers released EXTREME to ELEVATED SHORT. UST 10Y asset managers hold the duration long at z +2.42. Neither is a clean options-hedging read: UST 5Y OptZ +1.61 leans the opposite way. UST 10Y OptZ +0.75 is not stretched. Measured 4-week realized vol after weeks in these regimes: UST 5Y realized vol 1.16x the all-week average (n=77). UST 10Y realized vol 1.01x (n=54). That is modest at the belly and none at the 10Y.
- The front end eased on both sides. UST 2Y dealers released ELEVATED to MODERATE SHORT and 2Y leveraged funds stepped EXTREME to ELEVATED LONG on the z scale, though the leveraged book is still net short outright. The 30Y leveraged regime held EXTREME LONG at the 99th percentile of its range, again a lighter-than-usual leveraged short rather than a long.
- Euro leveraged funds pressed to an EXTREME SHORT, the week’s main FX development. The leveraged euro short sits at the bottom of its two-year range; dealers are net short the euro as well, so the euro long sits with asset managers. AUD dealers stepped NEUTRAL to MODERATE LONG on an event z of +2.28, and GBP dealers hold just under EXTREME at z +1.99. GBP lost last week’s options corroboration (OptZ -0.41).
- Elsewhere the board held its stretches. The Bitcoin dealer structural long sits at the 0.0th percentile of its range against leveraged funds that stepped MODERATE to ELEVATED LONG on the z scale while staying net short outright. The equity dealer average is +0.35z, and Natural Gas Commercials released MODERATE LONG to NEUTRAL. Board stress: 5 of 24 groups at |z| above 1.5.
- Catalyst line: CPI was released Oct 14, inside the snapshot-to-publication window; FOMC (Oct 28, 12 days) and PCE (Oct 29, 13 days) both fall inside the 14-day horizon and hit the 5Y/10Y dealer stretch, the SOFR book and the euro leveraged short; NFP (Nov 6) sits outside it.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-10-13 Tuesday snapshot; the price moves below run through Friday October 16 on a different clock and do not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | -1.99% | ES=F |
| Nasdaq | -4.64% | NQ=F, the weakest equity index |
| Russell 2000 | -2.33% | RTY=F |
| VIX | +30.91% | ^VIX 19.99, up from 15.27 |
| Bitcoin | -2.20% | BTC-USD |
| Ether | -3.76% | ETH-USD |
| UST 2Y | +0.15% | ZT=F futures up = front-end yields slightly down |
| UST 5Y | +0.49% | ZF=F futures up = belly yields down |
| UST 10Y | +0.78% | ZN=F futures up = yields down |
| UST 30Y | +1.75% | ZB=F futures up = long-end yields down, the largest rates move |
| Dollar Index | -0.37% | DX-Y.NYB, USD down |
| EUR | +0.53% | 6E=F up = euro up vs dollar |
| GBP | +0.54% | 6B=F up = sterling up vs dollar |
| AUD | -0.67% | 6A=F down = Aussie down vs dollar |
| MXN | -1.19% | 6M=F down = peso down vs dollar |
| WTI Crude | +4.99% | CL=F |
| Natural Gas | -5.03% | NG=F |
CPI was released Wednesday, October 14, inside the window. The dominant drivers were an equity selloff that headlines tie to worries about the AI trade and higher oil prices, which hit the Nasdaq hardest and lifted VIX, and Fed commentary (Daly saying hikes are likely needed but not urgently, Williams saying the Fed may not have to hike in 2027) alongside a Treasury rally led by the long end. This is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund or asset manager repositioning, and the next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 5Y | DEALER SHORT STEPPED UP ON OUTSIZED OPEX FLOW | -1.14 to -1.86 (Δ -0.72) | +1.62 to +1.63 (Δ +0.01) | dlr MODERATE to ELEVATED SHORT; lev ELEVATED LONG (held) | dealer 3.8th pctl, net -918,044; lev net -2,104,391, still short outright; AM net +2,984,952 holds the long; small traders z -1.50; OpEx event extreme ^ |
| 2 | UST 10Y | EXTREME RELEASED, AM DURATION LONG AT A RANGE HIGH | -2.06 to -1.94 (Δ +0.12) | -0.54 to -0.76 (Δ -0.22) | dlr EXTREME to ELEVATED SHORT; lev MODERATE SHORT (held) | dealer 3.8th pctl, net -632,813, WoW +9,220; AM net +2,898,562; lev net -2,205,937; Other Reportables z -2.44 |
| 3 | EUR | LEV SHORT PRESSED TO EXTREME | +1.34 to +1.42 (Δ +0.08) | -1.46 to -2.15 (Δ -0.69) | dlr MODERATE LONG (held); lev MODERATE to EXTREME SHORT | dealer net -164,763 (short euro, high end of its short range, not a long), WoW +11,751; lev net -68,001 short euro; AM net +199,918 holds the euro long (z -1.13); OptZ=+1.14 |
| 4 | UST 2Y | FRONT END RELEASED ON BOTH SIDES | -1.60 to -1.33 (Δ +0.27) | +2.25 to +1.86 (Δ -0.39) | dlr ELEVATED to MODERATE SHORT; lev EXTREME to ELEVATED LONG | dealer 11.5th pctl, net -481,721, WoW +26,730; lev net -1,367,408, still short outright; AM z -1.17; small traders z -1.90, washed out; OptZ=+0.03 |
| 5 | UST 30Y | LEV EXTREME HELD, DEALERS NEUTRAL | +0.15 to +0.40 (Δ +0.25) | +2.08 to +2.35 (Δ +0.27) | dlr NEUTRAL (held); lev EXTREME LONG (held) | dealer net -179,299, WoW +13,378; lev net -154,020, still short outright; AM z -1.99; Other Reportables z -3.75; small traders z -1.78; OptZ=+2.02 |
| 6 | AUD | REGIME STEP ON OUTSIZED OPEX FLOW | +0.43 to +0.72 (Δ +0.29) | +1.29 to +1.16 (Δ -0.13) | dlr NEUTRAL to MODERATE LONG; lev MODERATE LONG (held) | dealer net +48,901 long AUD, WoW +19,936, flow z +1.55 ^; lev net +50,591 long; AM net -115,920 (z -2.60); OptZ=+1.90 |
| 7 | GBP | NEAR-EXTREME DEALER LONG, OPTIONS SUPPORT GONE | +1.97 to +1.99 (Δ +0.02) | -1.54 to -1.67 (Δ -0.13) | dlr ELEVATED LONG (held); lev ELEVATED SHORT (held) | dealer 97.1st pctl, genuine long +150,796; lev net +10,313, long outright; AM net -145,735 holds the short (z -1.74); small traders z -1.60; top-4 51.3% # |
| 8 | Bitcoin | STRUCTURAL LONG AT ITS RANGE LOW, LEV STEP | -1.58 to -1.73 (Δ -0.15) | +1.42 to +1.59 (Δ +0.17) | dlr ELEVATED SHORT (held); lev MODERATE to ELEVATED LONG | dealer net +1,841 (structural long, not short), WoW -498; lev net -5,844, short outright; AM z -1.33; top-4 63.9%; OptZ=-0.01 caveat |
| 9 | SOFR 3M | DEALER STRETCH HELD, LEV RELEASED | +1.64 to +1.51 (Δ -0.13) | -1.52 to -1.37 (Δ +0.15) | dlr ELEVATED LONG (held); lev ELEVATED to MODERATE SHORT | dealer 81.7th pctl, net +2,720,960, WoW -98,298; lev net -2,245,507; AM z -1.32; 37.0% of lev gross in spread structure; 83L/92S #; OptZ=-2.82 caveat (opposite way) |
| 10 | Natural Gas | COMMERCIALS BACK TO NEUTRAL, MANAGED MONEY RELEASED | +0.55 to +0.43 (Δ -0.12) | -1.60 to -1.27 (Δ +0.33) | Commercials MODERATE LONG to NEUTRAL; Managed Money (lev) ELEVATED to MODERATE SHORT | Commercials net -10,881 (hedge lighter than usual, still short); Managed Money net -126,481 short; Swap Dealers z +2.17; 49.4% of Managed Money gross in spreads |
| 11 | WTI Crude | OUTSIZED HEDGER BUILD | +1.13 to +1.41 (Δ +0.28) | -0.55 to -0.76 (Δ -0.21) | Commercials MODERATE LONG (held); Managed Money (lev) MODERATE SHORT (held) | Commercials 88.5th pctl, net +353,143 (genuinely net long for a hedger book), WoW +18,133, flow z +1.52 ^; Managed Money net +40,574, still long outright |
| 12 | VIX | LOW PROTECTION DEMAND, LEV RELEASED | +1.17 to +1.09 (Δ -0.08) | +1.55 to +1.37 (Δ -0.18) | dlr MODERATE LONG (held); lev ELEVATED to MODERATE LONG | dealer 87.5th pctl, net +70,048 long VIX = low protection demand; AM net -77,295 short vol at z -2.84; lev net +1,105; 30.7% of lev gross in spread structure |
| 13 | Russell 2000 | LEV SHORT RELEASED A TIER | +0.78 to +0.71 (Δ -0.07) | -1.66 to -1.16 (Δ +0.50) | dlr MODERATE LONG (held); lev ELEVATED to MODERATE SHORT | dealer 68.3rd pctl, genuine long +57,503, WoW -3,890; lev net -91,647 short; AM z -0.27; OptZ=+0.16 |
| 14 | MXN | FOUR-WEEK DEALER BUILD | +1.04 to +1.31 (Δ +0.27) | +1.45 to +1.06 (Δ -0.39) | dlr MODERATE LONG (held); lev MODERATE LONG (held) | dealer net +14,131 long peso, WoW +12,910; lev net +63,564 long peso; AM z -2.34; event z +1.40 |
| 15 | Nasdaq (Mini) | DEALERS ADDING SHORTS | -0.58 to -0.75 (Δ -0.17) | +0.53 to +0.87 (Δ +0.34) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer net -77,932, WoW -5,370; lev net -11,593, short outright; OptZ=-2.33; NDX Consol dlr -0.58 to -0.74 (Δ -0.16), Consol lev +0.42 to +0.61 (Δ +0.19), up a tier |
| 16 | S&P 500 (E-Mini) | QUIET, LESS SHORT THAN USUAL | +1.14 to +1.11 (Δ -0.03) | -0.85 to -0.75 (Δ +0.10) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer 88.5th pctl, net -602,358 (less short than usual, not long); lev net -408,726; AM z -0.24; OptZ=-1.55; Consol dlr +1.10 to +1.07 (Δ -0.03) |
| 17 | USD Index | AM HOLDS THE DOLLAR LONG, LEV STEP | -1.27 to -1.23 (Δ +0.04) | +0.49 to +0.62 (Δ +0.13) | dlr MODERATE SHORT (held); lev NEUTRAL to MODERATE LONG | dealer 14.4th pctl, net -19,573 (short DXY); AM net +18,164 long DXY (z +1.18); small traders z +1.12; top-4 70.3% |
| 18 | CHF | LEV SHORT DEEPENED | +0.94 to +0.74 (Δ -0.20) | -0.87 to -1.43 (Δ -0.56) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net +59,514 (genuine long franc); lev net -14,941; top-4 71.3%; OptZ=+1.61 |
| 19 | Ether | LEV STEP FROM NEUTRAL | +0.08 to -0.16 (Δ -0.24) | +0.35 to +0.72 (Δ +0.37) | dlr NEUTRAL (held); lev NEUTRAL to MODERATE LONG | dealer net +8,300 (structural long); lev net -6,283, short outright; top-4 80.1% |
| 20 | Gold | HEDGERS HIGH, QUIET | +1.31 to +1.35 (Δ +0.04) | -0.60 to -0.69 (Δ -0.09) | Commercials MODERATE LONG (held); Managed Money (lev) MODERATE SHORT (held) | Commercials 96.2nd pctl, net -17,681 hedge; Managed Money net +111,079, long outright |
| 21 | Silver | QUIET | +1.14 to +1.18 (Δ +0.04) | -1.28 to -1.40 (Δ -0.12) | Commercials MODERATE LONG (held); Managed Money (lev) MODERATE SHORT (held) | Commercials net -15,801 hedge; Managed Money net +5,619, long outright |
| 22 | Copper | QUIET | -0.94 to -0.84 (Δ +0.10) | +0.76 to +0.74 (Δ -0.02) | Commercials MODERATE SHORT (held); Managed Money (lev) MODERATE LONG (held) | Commercials net -90,466 hedge; Managed Money net +61,058 long; Other Reportables z +1.16 |
| 23 | CAD | QUIET AT NEUTRAL | -0.01 to +0.01 (Δ +0.02) | -0.99 to -1.38 (Δ -0.39) | dlr NEUTRAL (held); lev MODERATE SHORT (held) | dealer net +120,981 (genuine long CAD); lev net -88,112 short CAD; top-4 66.7% |
| 24 | JPY | QUIET | -0.21 to -0.11 (Δ +0.10) | +0.35 to +0.13 (Δ -0.22) | dlr NEUTRAL (held); lev NEUTRAL (held) | dealer net -73,811 (short yen), WoW +11,094; lev net -33,673 short yen; AM z +0.63 |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
The curve’s dealer stress rotated rather than resolved. Last week the release ran through the 2Y and 5Y while the 10Y held its extreme; this week the 10Y and 2Y eased a tier and the belly went the other way, with 5Y dealers adding shorts far faster than is typical for an OpEx week. In both the 5Y and 10Y the long sits with asset managers, and leveraged funds are net short at both tenors, so this is not a dealer-versus-leveraged standoff on the outright book: the 5Y extremes oppose each other only on the z scale; both books are short outright. The 5Y options book leans against the futures stretch and the 10Y caveat is unchanged, so read both as basis or directional hedging footprints, not an options-hedging book. The measured vol tilt is mild at the belly and absent at the 10Y.
The front end eased on both sides: 2Y dealers covered and the leveraged “long” label, which describes a lighter-than-usual short, came off its extreme; 2Y small-trader positioning sits washed out at the low end of its range. The 30Y leveraged book holds its extreme for the same reason: a lighter-than-usual short, still short outright, with other reportables at the bottom of their range. SOFR dealers keep the stretched long with the leveraged short released a tier; a large share of that leveraged gross is spread structure and the dealer options book still leans the opposite way, so read the dealer stretch with the same caution as recent weeks.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
The euro is the FX story. Leveraged funds pressed their short to the bottom of its two-year range while dealers kept a multi-week build, yet both cohorts are net short the euro, so they are on the same side and asset managers hold the long; the crowded-short label is a z-scale read, not a counterparty standoff. Dealers have built their net position higher for four weeks across EUR, GBP, AUD, CAD, JPY and MXN, leaving the buy-side shorter those currencies, which coheres with asset managers holding a dollar long; that is one dollar-supportive buy-side story, not eight.
AUD dealers stepped into a long on unusually heavy OpEx-week flow, opposite leveraged funds that are long too, so the short sits with asset managers at the deepest point of their range, a pattern that in currencies often reflects hedging rather than a directional view. MXN dealers extended a four-week build on the same asset manager short. GBP is the standing near-extreme: dealers hold a genuine sterling long and leveraged funds are long outright alongside them, leaving asset managers as the short, but the options book no longer corroborates it, so it now reads as a basis or directional footprint rather than the board’s one options-supported extreme. Historical analogs: 5 prior ELEVATED LONG episodes (2024-04-23 to 2026-07-07) saw sterling bullish in 5 of 5 over 4 weeks with a median 4-week return of +1.7%, against an unconditional base rate of +0.0% median and 51% bullish across all 885 weeks; that deviates from the base rate, but five episodes, four since December 2025, is thin context, and the window is anchored to the Tuesday snapshot. The CHF leveraged short deepened within its tier; CAD and JPY sat quiet.
Equities (S&P 500, Nasdaq, Russell 2000)
The equity board stays rotated inside a moderate band. Nasdaq dealers added short exposure for a second week while the consolidated leveraged book stepped up a tier on the z scale, still net short outright; S&P 500 dealers remain less short than usual on a multi-week covering trend against a leveraged short. Russell 2000 leveraged funds released a tier but remain the short against a genuinely long dealer book. The equity dealer average stays mild. VIX shows low protection demand: dealers are long VIX and asset managers remain deep vol sellers, while the leveraged long vol position eased a tier and is heavy in spread structures, so its directional read overstates conviction.
Crypto (Bitcoin, Ether)
Bitcoin dealers remain structurally net long; the ELEVATED SHORT label means the long has thinned to the bottom of its two-year range, not that dealers are short. Leveraged funds stepped up a tier on the z scale while net short outright, so the apparent standoff is
again a lighter-than-usual leveraged short against a thin dealer long. Ether dealers sit at neutral, so the intra-crypto gap remains Bitcoin-specific. Historical analogs: 5 prior ELEVATED SHORT episodes (2022-11-15 to 2023-12-26) were bullish in 3 of 5 over 4 weeks with a median 4-week return of +2.9%, against an unconditional base rate of +2.1% median and 57% bullish across 627 weeks, which is unremarkable.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Natural Gas Commercials eased back to the middle of their hedging range and Managed Money released its short a tier, while Swap Dealers keep an unusually large long; the hedger-versus-speculator tension narrowed. WTI Commercials added sharply to a book that is genuinely net long for hedgers, with Managed Money trimming a still-long position, so hedgers and speculators sit on the same side of crude. Gold Commercials remain high in their hedging range, and silver and copper sat quiet. This is positioning state only.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (ES) | 6,638-6,835 | 7,701 | +14.2% | 7,268-7,466 | +3.9% |
| Nasdaq (NQ) | 29,356-30,363 | 29,369 | -1.4% | 29,658-30,815 | -3.8% |
| Russell 2000 | 2,825-2,924 | 2,735 | -5.2% | 2,848-2,945 | -5.9% |
| VIX | 15.46-18.78 | 19.93 | +24.3% | – | – |
| Bitcoin | 76,620-83,215 | 81,285 | +1.8% | 74,231-80,627 | +4.8% |
| Ether | 2,325-2,559 | 2,403 | -0.6% | 2,322-2,530 | +0.1% |
| USD Index | 99.90-101.25 | 101.80 | +1.0% | – | – |
| Gold (Comm / MM) | 4,168-4,383 | 4,191 | -2.5% | 3,968-4,181 | +2.5% |
| Silver (Comm / MM) | 57.96-63.93 | 57.22 | -4.8% | 64.98-72.04 | -16.1% |
| WTI Crude (Comm / MM) | 79.12-92.38 | 98.85 | +13.1% | 80.91-93.37 | +13.4% |
| Copper (Comm / MM) | 5.84-6.09 | 6.57 | +10.6% | 6.01-6.26 | +7.7% |
| Natural Gas (Comm / MM) | 2.89-3.19 | 3.12 | +2.6% | 2.86-3.10 | +4.3% |
The Nasdaq now trades below the leveraged basis zone and at the bottom edge of the dealer zone, and the Russell 2000 trades below both zones. VIX and WTI crude trade above their zones, silver sits below both the Commercial and Managed Money zones, and Bitcoin, Ether and natural gas sit inside their dealer or Commercial zones. These are descriptive P&L facts about the aggregate books, not triggers; in 2026 testing, a basis cross has not been followed by covering.
BOTTOM LINE
Into the Oct 28 FOMC, the Treasury positioning risk to size around is the 5Y, where the dealer short is newest and built hardest for an OpEx week, but treat it as a basis or hedging footprint netted against an opposite-leaning options book, not an options-hedging accelerant; in FX, the euro is the one market where a leveraged crowd, rather than a dealer book, sits at a range extreme.
Data: CFTC COT Report 2026-10-13 | Prices as of 2026-10-16 | Analysis window: 104 weeks
Smart Money Pulse - '26 W41
Bond Dealers Stepped Back From the Edge, Five Days Before the Inflation Report
The most crowded corner of the Treasury market emptied out faster than it filled. As of Tuesday, dealers in the 2-Year and 5-Year Treasury had pulled well away from the bottom of their two-year ranges; the 5-Year dropped two full tiers in a single week on the biggest rates move on the board, with no Fed meeting or options expiration nearby to explain it.
That matters if you own a bond fund, because the pressure is now concentrated in one maturity instead of spread across several. The 10-Year Treasury, the maturity behind intermediate funds like IEF and a big slice of BND, is the only one still at an extreme, and CPI (the consumer price index, the monthly inflation report) lands on it Wednesday, October 14.
This is Tuesday’s picture. Since then the 2-Year and 5-Year have barely moved in price while the 30-Year firmed, which means long-term yields eased a little. Stocks slipped, led lower by the Nasdaq, and none of it tells us how dealers handled the week; next week’s report is the first that can.
This Week’s Positioning
The 2-Year and 5-Year Treasury: dealers let go of the floor
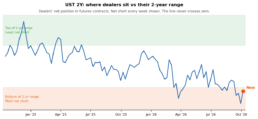
Dealers in the 2-Year climbed out of extreme territory into the stretched zone just above it (z=-1.60), and 5-Year dealers fell all the way back to a moderate short; both are still net short, just no longer pinned to the low end of their range. The 10-Year dealers covered too, but their short is still the deepest on the board, with the big asset managers holding the other side near the top of their own range. In the 2-Year and 5-Year the small-trader crowd has also pulled back to the low end of its usual long, so retail money has largely stepped away from short-term Treasuries rather than piling in.
Watch: CPI on October 14, the next major scheduled release aimed squarely at the 10-Year, the last maturity still sitting at an extreme.
Nasdaq: dealers leaned short out of nowhere
Nasdaq dealers added to their short in an unusually large one-week move, enough to push them from neutral into a moderate short. It is a mild reading rather than a crowded one, but it arrived with no calendar event behind it and it runs opposite to the S&P 500, where dealers are less short than usual. Since Tuesday the Nasdaq has been the weakest of the three major indexes, down a little over 1% as headlines focused on a stumble in the AI trade; that is price, not evidence that dealers did anything more.
Watch: the Nasdaq near 30,800, the top of the zone where the hedge fund crowd built its current position and about 1% below where the index sits now.
Bitcoin: the dealer cushion is the thinnest in two years
Dealers’ structural long in Bitcoin slid to the very bottom of its two-year range, into stretched territory (z=-1.58), though they are still net long. Past weeks like this saw Bitcoin higher a month later in 3 of 5 cases, close to its 57% base rate of rising in any four-week stretch, so the history says little either way. Since Tuesday Bitcoin has dropped about 3.6% to just under $83,000.
Watch: whether Bitcoin holds above $76,600, the bottom of the zone where dealers built their long; spot ETFs like IBIT track the same price.
The Mexican peso: dealers dropped their bet against it
Peso dealers covered on the largest weekly move anywhere on the board and flipped to a token net long, capping four straight weeks of building. The hedge fund crowd is long the peso too, so the bet against it now sits with the big asset managers, whose short is the deepest in their two-year range, a posture that in currencies often reflects hedging rather than a view. The peso has fallen nearly 3% against a firmer U.S. dollar since Tuesday, the biggest currency move of the week.
Watch: next week’s report, the first to show whether dealers kept their new long through the slide; it matters most if you hold an emerging-markets fund like VWO with Mexico exposure.
Elsewhere: the 30-Year Treasury’s hedge fund crowd reached the light end of its short range, an extreme on paper that still means short outright, while 30-Year dealers sit mid-range. Dealers in the British pound hold a genuine long just shy of extreme, and SOFR futures (the market’s bet on short-term interest rates) kept their opposed stretch for another week. The hedge fund short in the Russell 2000 eased back from extreme to stretched, institutions remain the heaviest sellers of volatility protection on the board with the VIX near 14.8, and euro and Australian dollar dealers covered heavily. In commodities, natural gas’s speculative crowd pressed its short into stretched territory while its hedgers carry a lighter hedge than usual; gold, silver, crude and copper are background.
Know Where You Stand
- Before CPI on October 14, find out which part of the Treasury market your bond fund actually owns. A short-term fund like SHY lives near the 2-Year, where the crowding just eased, while IEF and much of BND sit closer to the 10-Year, the one maturity still stretched to an extreme, so the same inflation print can land differently on each.
- Add up how much of your stock money is really one tech bet. SPY’s largest holdings are the same megacap names that drive QQQ, so if you own both, know your combined tech weight before the Fed’s rate decision (the FOMC meeting, October 28) and PCE (the Fed’s preferred inflation measure, October 29) land back to back.
- If you hold a spot Bitcoin ETF, size it for swings you have already seen. Bitcoin gave up about 3.6% between Tuesday and Friday; whether that holding is 1% or 10% of your account, decide now what move you could sit through, since nothing in this data says which way the next one goes.
Data: CFTC COT Report 2026-10-06 | Prices as of 2026-10-09 | 104-week lookback
Liquidity Trajectory '26 W41
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-10-06 | Generated: 2026-10-09 17:06 ET
EXECUTIVE SUMMARY
- The Treasury dealer short extreme broke across the 2Y and 5Y. UST 5Y dealers released two tiers from EXTREME to MODERATE SHORT on a flow z of +3.32 and UST 2Y dealers released EXTREME to ELEVATED SHORT on +2.52, both outsized with no FOMC or OpEx event nearby. UST 10Y dealers covered too (flow z +2.22) but still sit EXTREME SHORT at -2.06, the 1.9th percentile, against an asset manager duration long at z +2.28. Both the 2Y and 10Y readings carry options caveats (OptZ +0.43 and +0.79), so read them as basis or directional footprints, not options hedging. Measured 4-week realized vol after weeks in these regimes: UST 2Y realized vol 1.26x the all-week average (n=68); UST 10Y realized vol 0.99x (n=59). That is modest amplification at the front and none at the 10Y.
- The leveraged side of the curve did not follow the dealers out. The 2Y leveraged regime held EXTREME LONG at +2.25 and the 30Y leveraged regime stepped from ELEVATED to EXTREME LONG at +2.08, yet both books remain net short outright (-1,257,484 and -189,678), so these are leveraged shorts at the light end of their range, not leveraged longs. SOFR 3M dealers held ELEVATED LONG at +1.64 for a fourth straight week of declining dealer net.
- Two dealer books stepped to new tiers outside rates. Nasdaq dealers moved NEUTRAL to MODERATE SHORT on a consolidated flow z of -2.15, and the Bitcoin dealer structural long slid from MODERATE to ELEVATED SHORT on the z scale at the 0.0th percentile, still net long +2,339 contracts. The equity dealer average is +0.43z; Russell 2000 leveraged funds released EXTREME to ELEVATED SHORT.
- FX dealers covered across the commodity currencies and the euro. MXN dealers stepped NEUTRAL to MODERATE LONG on a flow z of +3.36, enough to flip the dealer book to a token +1,221 contracts long; AUD (+2.95) and EUR (+1.93) also printed outsized covering flow. GBP dealers sit at +1.97, a hair under EXTREME, and remain the board’s one options-corroborated extreme (OptZ +1.80). In commodities, Natural Gas Commercials stepped NEUTRAL to MODERATE LONG while Managed Money stepped to ELEVATED SHORT. Board stress: 5 of 24 groups at |z| above 1.5.
- Catalyst line: CPI prints Oct 14, five days out, on the 10Y extreme, the 2Y stretch and the SOFR book; FOMC (Oct 28) and PCE (Oct 29) fall just outside the 14-day window.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-10-06 Tuesday snapshot; the price moves below run through Friday October 9 on a different clock and do not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | -0.11% | ES=F, flat |
| Nasdaq | -1.13% | NQ=F, the weakest equity index |
| Russell 2000 | -0.86% | RTY=F |
| VIX | -1.13% | ^VIX 14.84 |
| Bitcoin | -3.60% | BTC-USD |
| Ether | -8.01% | ETH-USD, the largest move on the board |
| UST 2Y | 0.00% | ZT=F unchanged, front-end yields flat |
| UST 5Y | +0.02% | ZF=F flat |
| UST 10Y | +0.10% | ZN=F futures up = yields slightly down |
| UST 30Y | +0.64% | ZB=F futures up = long-end yields down, the largest rates move |
| Dollar Index | +0.38% | DX-Y.NYB, USD up |
| EUR | -0.31% | 6E=F down = euro down vs dollar |
| GBP | -0.29% | 6B=F down = sterling down vs dollar |
| MXN | -2.81% | 6M=F down = peso down vs dollar, the largest FX move |
| Natural Gas | +2.89% | NG=F |
| Copper | +1.74% | HG=F |
No scheduled macro release landed in the window. The drivers were an AI-trade stumble that headlines tie to an OpenAI revenue setback, which hit the Nasdaq hardest, and a crypto liquidation that pushed Bitcoin below $83K, while the White House escalated its effort to remove Fed Governor Lisa Cook; Treasury futures held flat at the front and firmed at the long end despite yield-anxiety headlines. This is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund or asset manager repositioning, and the next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 2Y | EXTREME RELEASED ON OUTSIZED COVERING, LEV EXTREME HELD | -2.42 to -1.60 (Δ +0.82) | +2.61 to +2.25 (Δ -0.36) | dlr EXTREME to ELEVATED SHORT; lev EXTREME LONG (held) | dealer 4.8th pctl, net -508,451, WoW +83,045, flow z +2.52^; lev net -1,257,484, still short outright; AM net +1,679,087 (z -1.73); small traders z -1.74, washed out; OptZ=+0.43 caveat |
| 2 | UST 5Y | TWO-TIER RELEASE ON THE BOARD’S LARGEST RATES FLOW | -2.44 to -1.14 (Δ +1.30) | +1.95 to +1.62 (Δ -0.33) | dlr EXTREME to MODERATE SHORT; lev ELEVATED LONG (held) | dealer 11.5th pctl, net -835,892, WoW +144,190, flow z +3.32^; lev net -2,127,567, still short outright; small traders z -1.86; OptZ=-0.33 |
| 3 | UST 10Y | EXTREME HELD DESPITE OUTSIZED COVERING | -2.75 to -2.06 (Δ +0.69) | -0.19 to -0.54 (Δ -0.35) | dlr EXTREME SHORT (held); lev NEUTRAL to MODERATE SHORT | dealer 1.9th pctl, net -642,033, WoW +94,552, flow z +2.22^; AM net +2,828,139 holds the long; lev net -2,139,785; Other Reportables z -2.15; OptZ=+0.79 caveat |
| 4 | GBP | NEAR-EXTREME DEALER LONG, OPTIONS-CORROBORATED | +1.75 to +1.97 (Δ +0.22) | -2.14 to -1.54 (Δ +0.60) | dlr ELEVATED LONG (held); lev EXTREME to ELEVATED SHORT | dealer 97.1st pctl, genuine long +148,033, WoW +13,400; lev net +12,432, long outright; AM net -145,442 holds the short (z -1.76); small traders z -1.59; top-4 51.0% #; OptZ=+1.80 corroborates |
| 5 | SOFR 3M | OPPOSED STRETCH HELD, FOURTH WEEK OF DEALER DECLINE | +1.80 to +1.64 (Δ -0.16) | -1.61 to -1.52 (Δ +0.09) | dlr ELEVATED LONG (held); lev ELEVATED SHORT (held) | dealer 82.7th pctl, net +2,819,258, WoW -141,273; lev net -2,353,716; AM z -1.37; 37.4% of lev gross in spread structure; 81L/94S #; OptZ=-2.96 caveat (opposite way) |
| 6 | Bitcoin | STRUCTURAL LONG STEPPED TO ELEVATED LOW | -1.35 to -1.58 (Δ -0.23) | +1.45 to +1.42 (Δ -0.03) | dlr MODERATE to ELEVATED SHORT; lev MODERATE LONG (held) | dealer 0.0th pctl, net +2,339 (structural long, not short), WoW -341; lev net -6,852, short outright; AM z -1.41; top-4 61.8%; OptZ=-0.09 caveat |
| 7 | MXN | REGIME STEP ON THE BOARD’S LARGEST FLOW Z | +0.09 to +1.04 (Δ +0.95) | +1.67 to +1.45 (Δ -0.22) | dlr NEUTRAL to MODERATE LONG; lev ELEVATED to MODERATE LONG | dealer net +1,221 (flipped from short to a token long), WoW +43,649, flow z +3.36^; lev net +74,927 long peso; AM z -2.36; OptZ=+2.05 |
| 8 | Nasdaq (NDX Consol) | REGIME STEP ON OUTSIZED SELLING | -0.09 to -0.58 (Δ -0.49) | +0.14 to +0.42 (Δ +0.28) | dlr NEUTRAL to MODERATE SHORT; lev NEUTRAL (held) | dealer net -68,781, WoW -14,788, flow z -2.15^; lev net -26,738, short outright; AM z +0.43; OptZ=-3.39; Mini dlr also NEUTRAL to MODERATE SHORT, Mini lev z +0.53 |
| 9 | Natural Gas | COMMERCIALS STEP, MANAGED MONEY TO ELEVATED SHORT | +0.32 to +0.55 (Δ +0.23) | -1.43 to -1.60 (Δ -0.17) | Commercials NEUTRAL to MODERATE LONG; Managed Money (lev) MODERATE to ELEVATED SHORT | Commercials net -8,229 (hedge lighter than usual, still short); Managed Money net -144,537 short; Swap Dealers z +2.20; 51.8% of Managed Money gross in spreads |
| 10 | UST 30Y | LEV STEP TO EXTREME, DEALERS NEUTRAL | +0.33 to +0.15 (Δ -0.18) | +1.51 to +2.08 (Δ +0.57) | dlr NEUTRAL (held); lev ELEVATED to EXTREME LONG | dealer net -192,677, WoW -11,878; lev net -189,678, still short outright; AM z -1.81; Other Reportables z -3.38; top-4 34.7%; OptZ=+1.98 |
| 11 | Russell 2000 | LEV RELEASED FROM EXTREME | +1.03 to +0.78 (Δ -0.25) | -2.03 to -1.66 (Δ +0.37) | dlr MODERATE LONG (held); lev EXTREME to ELEVATED SHORT | dealer 72.1st pctl, genuine long +61,393, WoW -16,298; lev net -105,317 short; AM z +0.06; OptZ=+0.68 |
| 12 | VIX | LOW PROTECTION DEMAND, LEV FLIPPED LONG VOL | +1.13 to +1.17 (Δ +0.04) | +1.10 to +1.55 (Δ +0.45) | dlr MODERATE LONG (held); lev MODERATE to ELEVATED LONG | dealer 88.5th pctl, net +71,707 long VIX = low protection demand; AM net -80,614 short vol at z -3.13, the board’s most negative AM reading; lev net +5,494; 32.8% of lev gross in spread structure |
| 13 | EUR | OUTSIZED DEALER COVERING, FOURTH WEEK OF BUILD | +1.06 to +1.34 (Δ +0.28) | -1.33 to -1.46 (Δ -0.13) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -176,514 (short euro, high end of its short range, not a long), WoW +35,652, flow z +1.93^; lev net -44,261 short euro; AM net +189,881 holds the euro long (z -1.27); OptZ=+1.28 |
| 14 | Copper | OUTSIZED HEDGER COVERING | -1.39 to -0.94 (Δ +0.45) | +1.50 to +0.76 (Δ -0.74) | Commercials MODERATE SHORT (held); Managed Money MODERATE LONG (held) | Commercials 22.1st pctl, net -92,720 hedge, WoW +11,620, flow z +1.79^; Managed Money net +61,134 long; Other Reportables z +1.27 |
| 15 | S&P 500 (E-Mini) | DEALERS STILL COVERING, LEV TO MODERATE SHORT | +1.10 to +1.14 (Δ +0.04) | -0.28 to -0.85 (Δ -0.57) | dlr MODERATE LONG (held); lev NEUTRAL to MODERATE SHORT | dealer 89.4th pctl, net -600,841 (less short than usual, not long), WoW +6,147; lev net -415,087; AM z -0.39; OptZ=-1.55; Consol dlr +1.06 to +1.10 (Δ +0.04) |
| 16 | AUD | OUTSIZED FLOW FROM A NEUTRAL BASE | -0.14 to +0.43 (Δ +0.57) | +1.50 to +1.29 (Δ -0.21) | dlr NEUTRAL (held); lev MODERATE LONG (held) | AUD dealer net +28,965 (flipped to long), WoW +37,752, flow z +2.95^; lev net +54,133 long; AM z -2.26 |
| 17 | WTI Crude | MANAGED MONEY TO MODERATE SHORT ON THE Z SCALE | +0.88 to +1.13 (Δ +0.25) | -0.12 to -0.55 (Δ -0.43) | Commercials MODERATE LONG (held); Managed Money (lev) NEUTRAL to MODERATE SHORT | WTI Commercials net +335,010 (genuinely net long for a hedger book), 85.6th pctl, WoW +15,471; Managed Money net +53,598, still long outright |
| 18 | Gold | HEDGERS HIGH, QUIET | +1.26 to +1.31 (Δ +0.05) | -0.33 to -0.60 (Δ -0.27) | Commercials MODERATE LONG (held); Managed Money (lev) NEUTRAL to MODERATE SHORT | Commercials 91.3rd pctl, net -18,984 hedge; Managed Money net +114,820, long outright |
| 19 | USD Index | QUIET, AM HOLDS THE DOLLAR LONG | -1.16 to -1.27 (Δ -0.11) | +0.44 to +0.49 (Δ +0.05) | dlr MODERATE SHORT (held); lev NEUTRAL (held) | dealer 12.5th pctl, net -19,790 (short DXY); AM net +19,096 long DXY (z +1.29); small traders z +1.44; top-4 65.2% |
| 20 | Silver | QUIET | +1.13 to +1.14 (Δ +0.01) | -1.30 to -1.28 (Δ +0.02) | Commercials MODERATE LONG (held); Managed Money MODERATE SHORT (held) | Commercials net -16,253 hedge; Managed Money net +7,528, long outright |
| 21 | CHF | DEALER LONG EASED | +1.30 to +0.94 (Δ -0.36) | -1.32 to -0.87 (Δ +0.45) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net +61,628 (genuine long franc); lev net -11,350; top-4 69.0%; OptZ=+2.56 |
| 22 | CAD | QUIET AT NEUTRAL | -0.26 to -0.01 (Δ +0.25) | -0.52 to -0.99 (Δ -0.47) | dlr NEUTRAL (held); lev MODERATE SHORT (held) | CAD dealer net +119,957 (genuine long CAD), WoW +20,133; lev net -79,625 short CAD; top-4 64.2% |
| 23 | JPY | QUIET | -0.23 to -0.21 (Δ +0.02) | +0.63 to +0.35 (Δ -0.28) | dlr NEUTRAL (held); lev MODERATE LONG to NEUTRAL | dealer net -84,905 (short yen); lev net -25,043 short yen; AM z +0.68 |
| 24 | Ether | QUIET AT NEUTRAL | +0.32 to +0.08 (Δ -0.24) | +0.30 to +0.35 (Δ +0.05) | dlr NEUTRAL (held); lev NEUTRAL (held) | dealer net +9,088 (structural long); lev net -7,949; top-4 76.0% |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
The curve story flipped from last week’s full-span dealer short extreme to a split curve. Dealers covered hard across the 2Y, 5Y and 10Y in the same week, with no calendar event to explain it, and the belly is now back inside normal range while the 10Y alone keeps its extreme. The 10Y short is matched by asset managers holding a duration long at the top of its two-year range rather than by a leveraged crowd, and its options caveat is unchanged, so it reads as a basis or hedging footprint rather than an options-hedging book; the 2Y caveat likewise stands. The standing realized-vol tilt is unchanged in kind: modest amplification after 2Y weeks in this regime, none at the 10Y.
The leveraged “extreme long” labels at the 2Y and 30Y are a sign trap. Both books are net short outright, so at the 2Y dealers and leveraged funds sit on the same short side and the long belongs to asset managers and other reportables; the opposed-extremes tag is a z-scale tension, not two cohorts on opposite sides of the trade. At the front end, SOFR dealers keep shedding their long for a fourth week against a leveraged short that is heavy in spread structures, and the dealer options book leans the opposite way, so read the futures stretch net of that offset.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
Dealers covered shorts broadly this week: MXN crossed into a new regime and turned the dealer book to a token long, while AUD flipped long from a neutral base and EUR dealers extended a four-week build. In the euro, dealers and leveraged funds are both net short, so they are on the same side and asset managers hold the long; the crowded-short label is relative, not a counterparty standoff. The dollar story is coherent: asset managers are long DXY and their euro long sits at the low end of its range, a consistent dollar-supportive buy-side lean, and the peso and AUD asset manager books are the deepest shorts in their two-year ranges, which in currencies often reflects hedging rather than a directional view.
GBP is the quiet standing extreme: dealers hold a genuine sterling long with options corroboration, so this is the one place the options-hedging hypothesis has support this week, while leveraged funds released a tier on the z scale but stay long outright alongside dealers, leaving asset managers as the short. Historical analogs: 5 prior ELEVATED LONG episodes (2024-04-23 to 2026-07-07) saw sterling bullish in 5 of 5 over 4 weeks with a median 4-week return of +1.7%, against an unconditional base rate of +0.0% median and 51% bullish across all 885 weeks. That deviates from the base rate, but five episodes, four of them clustered since December 2025, is thin historical context and not a signal; the window is anchored to the Tuesday snapshot.
Equities (S&P 500, Nasdaq, Russell 2000)
The equity board is rotating inside a moderate band. Nasdaq dealers added short exposure into a new regime on outsized selling with no calendar catalyst, while S&P 500 dealers kept covering and leveraged funds moved the opposite way, leaving the S&P dealer book less short than usual against a leveraged short that is building. Russell 2000 leveraged funds eased out of their extreme but remain the crowded short against a dealer book that is genuinely long; dealers trimmed that long this week, so the two cohorts are no longer pulling against each other as hard. The equity dealer average sits at the moderate long end, a mild rather than stretched read. VIX shows low protection demand: dealers are long VIX, asset managers are the deepest vol sellers on the board and leveraged funds flipped to a small net long vol position, though a third of their gross sits in spread structures, so the directional read overstates conviction.
Crypto (Bitcoin, Ether)
Bitcoin dealers remain structurally net long; the step to ELEVATED SHORT on the z scale means the long has thinned to the bottom of its two-year range, not that dealers are short. Leveraged funds are net short outright, so the crowded-long tag again describes a lighter-than-usual leveraged short. Ether dealers sit at neutral, so the intra-crypto gap is a Bitcoin-specific thinning rather than a sector-wide one. Historical analogs: 5 prior ELEVATED SHORT episodes (2022-11-15 to 2023-12-26) were bullish in 3 of 5 over 4 weeks with a median 4-week return of +2.9%, against an unconditional base rate of +2.1% median and 57% bullish across 626 weeks, which is unremarkable.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Natural Gas carries the hedger-versus-speculator tension: Commercials stepped to a lighter-than-usual hedge, still net short, while Managed Money pressed its short into elevated territory and Swap Dealers hold an unusually large long. Copper Commercials covered an outsized slice of their hedge, moving further off the low end of its range, while Managed Money cut its long. The rest sat quiet: gold Commercials remain high in their hedging range with Managed Money long outright, WTI Commercials hold an unusually net long book against a still-long Managed Money position and silver was unchanged. This is positioning state only.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (ES) | 6,635-6,833 | 7,866 | +16.7% | 7,268-7,466 | +6.1% |
| Nasdaq (NQ) | 29,362-30,295 | 31,129 | +4.4% | 29,658-30,815 | +1.9% |
| Russell 2000 | 2,825-2,924 | 2,824 | -2.1% | 2,848-2,945 | -2.9% |
| VIX | 15.46-18.78 | 14.84 | -7.4% | – | – |
| Bitcoin | 76,620-83,215 | 82,475 | +3.2% | 74,231-80,627 | +6.4% |
| Ether | 2,325-2,559 | 2,482 | +2.7% | 2,322-2,530 | +3.3% |
| USD Index | 99.90-101.25 | 102.22 | +1.4% | – | – |
| Gold (Comm / MM) | 4,168-4,383 | 4,220 | -1.8% | 3,968-4,181 | +3.2% |
| Silver (Comm / MM) | 57.96-63.93 | 61.11 | +1.7% | 64.98-72.04 | -10.4% |
| WTI Crude (Comm / MM) | 78.55-92.01 | 91.56 | +5.5% | 80.91-93.37 | +5.0% |
| Copper (Comm / MM) | 5.84-6.09 | 6.71 | +13.0% | 6.01-6.26 | +10.0% |
| Natural Gas (Comm / MM) | 2.84-3.15 | 3.20 | +6.3% | 2.86-3.10 | +7.0% |
Russell 2000 trades just below both the dealer and leveraged basis zones, and VIX sits below the dealer zone. Copper and natural gas trade above both zones, as do the S&P 500 and Bitcoin leveraged zones, while silver sits well below the Managed Money zone. These are descriptive P&L facts about the aggregate books, not triggers; tested 2026, no covering response follows a basis cross.
BOTTOM LINE
Going into CPI, the curve risk is narrower than a week ago: the belly dealer extreme is gone and the one remaining extreme, the 10Y short, is matched by asset manager duration and carries an options caveat, so treat it as a basis footprint to size around rather than an options-hedging book that would amplify the print.
Data: CFTC COT Report 2026-10-06 | Prices as of 2026-10-09 | Analysis window: 104 weeks
Liquidity Trajectory '26 W40
LIQUIDITY TRAJECTORY
CFTC Report Date: 2026-09-29 | Generated: 2026-10-02 15:55 ET
EXECUTIVE SUMMARY
- The dealer short extreme now runs the full 2Y-to-10Y span of the curve. UST 10Y and UST 2Y dealers both stepped from ELEVATED to EXTREME SHORT, joining the 5Y, and all three sit at the very bottom of their two-year range. The 10Y step came on the board’s most negative dealer flow z, with leveraged funds neutral and asset managers holding the duration long at z +2.20, so the 10Y short is matched by asset managers rather than a leveraged crowd. Every one of the three extremes carries an options caveat this week (the 5Y lost last week’s corroboration), so read them as basis or directional footprints, not options-hedging. Measured 4-week realized vol after weeks in this regime: UST 2Y realized vol 1.13x the all-week average (n=58); UST 5Y realized vol 1.19x (n=55); UST 10Y realized vol 0.99x (n=58). That is modest amplification at the front and belly and none at the 10Y.
- The long end and the front end decompressed around that belly. UST 30Y dealers released MODERATE SHORT to NEUTRAL on the largest flow z on the board while the 30Y leveraged crowd stepped down from EXTREME to ELEVATED LONG, and SOFR dealers released EXTREME to ELEVATED LONG, still opposed to an ELEVATED leveraged short. The 5Y leveraged crowd also released a tier; the 2Y crowd extended. Board stress: 5 of 24 groups at |z| above 1.5.
- Sterling is the board’s one opposed pair with options support, and it carries a sign trap. GBP dealers stepped to ELEVATED LONG on a genuine long of +134,633 contracts while the leveraged regime fell to EXTREME SHORT; leveraged funds are still net long +4,606 outright, so both cohorts sit on the long side and asset managers hold the sterling short. In equities, Russell 2000 leveraged funds stepped to an EXTREME SHORT against a dealer book that is genuinely long, and S&P 500 dealers kept covering; the equity dealer average is +0.67z.
- Elsewhere the week was releases, not builds. CAD and MXN dealers reset to NEUTRAL on outsized covering flow, CHF released ELEVATED to MODERATE LONG, Ether dealers reset to NEUTRAL on an outsized liquidation, copper Commercials released ELEVATED to MODERATE SHORT and WTI Managed Money dropped back to NEUTRAL. Bitcoin is the exception: the dealer structural long slid to the low end of its range on outsized flow.
- Catalyst line: NFP was released today (Oct 2), after the Tuesday snapshot, and landed on the SOFR and 2Y books; CPI follows Oct 14, twelve days out, on the 2Y, 5Y and 10Y extremes and the SOFR stretch.
SINCE THE SNAPSHOT
This brief reflects positioning as of the 2026-09-29 Tuesday snapshot; the price moves below run through Friday October 2 on a different clock and do not confirm any repositioning.
| Market | Since Tue | Level/Note |
|---|---|---|
| S&P 500 | +0.59% | ES=F |
| Nasdaq | +1.47% | NQ=F, the strongest equity index |
| Russell 2000 | +0.81% | RTY=F |
| VIX | -4.11% | ^VIX 15.38 |
| Bitcoin | +0.67% | BTC-USD |
| Ether | -0.47% | ETH-USD |
| UST 2Y | -0.19% | ZT=F futures down = front-end yields up |
| UST 5Y | -0.26% | ZF=F futures down = yields up |
| UST 10Y | -0.12% | ZN=F futures down = yields up |
| UST 30Y | -0.64% | ZB=F futures down = long-end yields up, the largest rates move |
| Dollar Index | +0.51% | DX-Y.NYB, USD up |
| GBP | +0.16% | 6B=F up = sterling up vs dollar |
| CAD | -0.27% | 6C=F down = loonie down vs dollar |
| MXN | -0.89% | 6M=F down = peso down vs dollar |
| Copper | +0.60% | HG=F |
| WTI Crude | +2.30% | CL=F, the largest commodity move |
NFP was released today; headlines describe cooler jobs growth supporting a Fed pause in October. The dominant driver of the window was the Treasury selloff: headlines put US bond yields at their highest since 2002 on Thursday, mortgage rates posted their largest weekly gain in four years and a Fed official called for 50 bps or more of hikes, before yields came off their highs Friday while equities finished strong on AI optimism. This is price action after the Tuesday snapshot; none of it confirms dealer, leveraged fund or asset manager repositioning, and the next positioning data is not visible until next week’s report.
POSITIONING TABLE
| Rank | Market | Signal | Dlr Z (prior to cur, Δ) | Lev Z (prior to cur, Δ) | Regime (+ transition) | Key Detail |
|---|---|---|---|---|---|---|
| 1 | UST 10Y | REGIME STEP TO EXTREME ON THE BOARD’S MOST NEGATIVE FLOW | -1.79 to -2.75 (Δ -0.96) | +0.19 to -0.19 (Δ -0.38) | dlr ELEVATED to EXTREME SHORT; lev NEUTRAL (held) | dealer 0.0th pctl, net -736,585, WoW -155,911, flow z -3.65^; AM long +2,776,531; lev net -2,036,432; Other Reportables z -1.98; OptZ=+0.97 caveat |
| 2 | UST 2Y | REGIME STEP TO EXTREME + OPPOSED EXTREMES | -1.86 to -2.42 (Δ -0.56) | +2.12 to +2.61 (Δ +0.49) | dlr ELEVATED to EXTREME SHORT; lev EXTREME LONG (held) | dealer 0.0th pctl, net -591,496, WoW -68,036, flow z -2.04^; lev net -1,165,980, still short outright; AM z -1.96; small traders z -1.85, washed out; OptZ=-0.09 caveat |
| 3 | UST 5Y | EXTREME HELD, LEV RELEASED A TIER | -2.10 to -2.44 (Δ -0.34) | +2.27 to +1.95 (Δ -0.32) | dlr EXTREME SHORT (held); lev EXTREME to ELEVATED LONG | dealer 0.0th pctl, net -980,082, WoW -46,766; lev net -1,985,787, still short outright; AM z -1.04; OptZ=-0.39 caveat (corroboration lost) |
| 4 | UST 30Y | REGIME RELEASE ON THE BOARD’S LARGEST FLOW | -0.83 to +0.33 (Δ +1.16) | +2.45 to +1.51 (Δ -0.94) | dlr MODERATE SHORT to NEUTRAL; lev EXTREME to ELEVATED LONG | dealer WoW +70,162, flow z +4.67^, net -180,799 (still short outright); lev net -251,395; AM z -1.32; Other Reportables z -3.01; top-4 36.1%; OptZ=+1.13 |
| 5 | GBP | REGIME STEP TO ELEVATED + OPPOSED Z EXTREMES | +1.29 to +1.75 (Δ +0.46) | -1.52 to -2.14 (Δ -0.62) | dlr MODERATE to ELEVATED LONG; lev ELEVATED to EXTREME SHORT | dealer 96.2nd pctl, WoW +26,491, flow z +1.60^; AM net -128,544 holds the short (z -1.39); 9L/5S #, top-4 48.3%; OptZ=+2.76 corroborates |
| 6 | SOFR 3M | EXTREME RELEASED, OPPOSED STRETCH HELD | +2.02 to +1.80 (Δ -0.22) | -1.68 to -1.61 (Δ +0.07) | dlr EXTREME to ELEVATED LONG; lev ELEVATED SHORT (held) | CME dealer 85.6th pctl, net +2,960,531, WoW -191,659; lev net -2,410,343; AM z -1.59; 37.3% of lev gross in spread structure; 84L/95S #; OptZ=-4.33 caveat; FMX venue a small new book (dealer net -1,173) |
| 7 | Russell 2000 | LEV STEP TO EXTREME AGAINST A DEALER LONG | +1.02 to +1.03 (Δ +0.01) | -1.85 to -2.03 (Δ -0.18) | dlr MODERATE LONG (held); lev ELEVATED to EXTREME SHORT | dealer 87.5th pctl, genuine outright long +77,691; lev net -114,554 short; AM z -0.08; OptZ=+1.04 |
| 8 | Bitcoin | STRUCTURAL LONG AT RANGE LOW ON OUTSIZED FLOW | -0.91 to -1.35 (Δ -0.44) | +1.25 to +1.45 (Δ +0.20) | dlr MODERATE SHORT (held); lev MODERATE LONG (held) | dealer 1.0th pctl, net +2,680 (structural long, not short), WoW -967, flow z -1.54^; lev net -6,856, short outright; AM z -1.41; top-4 66.3% |
| 9 | Copper | REGIME RELEASE FROM ELEVATED | -1.73 to -1.39 (Δ +0.34) | +1.73 to +1.50 (Δ -0.23) | Commercials ELEVATED to MODERATE SHORT; Managed Money ELEVATED to MODERATE LONG | Commercials 6.7th pctl, net -104,340 hedge, WoW +8,235; Managed Money net +78,058 long; Swap Dealers z -1.02; Other Reportables z +1.14; 29L/33S #; top-4 31.2% |
| 10 | CAD | REGIME RESET ON OUTSIZED COVERING | -0.72 to -0.26 (Δ +0.46) | +0.59 to -0.52 (Δ -1.11) | dlr MODERATE SHORT to NEUTRAL; lev MODERATE LONG to MODERATE SHORT | dealer net +99,824 (genuine long CAD), WoW +36,012, flow z +2.61^; lev net -69,644 short CAD; AM z +0.65; top-4 61.5% |
| 11 | MXN | REGIME RESET ON OUTSIZED COVERING | -0.63 to +0.09 (Δ +0.72) | +1.66 to +1.67 (Δ +0.01) | dlr MODERATE SHORT to NEUTRAL; lev ELEVATED LONG (held) | dealer net -42,428 (still short peso), WoW +32,268, flow z +2.49^; lev net +80,587 long peso; AM z -0.94; top-4 76.5% |
| 12 | Ether | REGIME RESET ON OUTSIZED LIQUIDATION | +0.98 to +0.32 (Δ -0.66) | -0.26 to +0.30 (Δ +0.56) | dlr MODERATE LONG to NEUTRAL; lev NEUTRAL (held) | dealer net +9,885 (structural long), WoW -2,487, flow z -2.16^; lev net -8,083; AM z -1.07; top-4 81.7% |
| 13 | CHF | ELEVATED RELEASED ON BOTH SIDES | +1.56 to +1.30 (Δ -0.26) | -1.74 to -1.32 (Δ +0.42) | dlr ELEVATED to MODERATE LONG; lev ELEVATED to MODERATE SHORT | dealer 86.5th pctl, net +65,448 (genuine long franc); lev net -13,995 short franc; small traders z -1.43; top-4 72.7%; OptZ=+2.07 |
| 14 | S&P 500 (E-Mini) | DEALERS STILL COVERING | +0.87 to +1.10 (Δ +0.23) | -0.33 to -0.28 (Δ +0.05) | dlr MODERATE LONG (held); lev NEUTRAL (held) | dealer 86.5th pctl, net -606,988 (less short than usual, not long), WoW +27,215; lev net -372,489; AM z -0.44; Other Reportables z -1.53; OptZ=-1.54; Consol dlr +0.82 to +1.06 (Δ +0.24), flow z +1.16 |
| 15 | VIX | LOW PROTECTION DEMAND, AM VOL SHORT DEEPENED | +1.04 to +1.13 (Δ +0.09) | +0.82 to +1.10 (Δ +0.28) | dlr MODERATE LONG (held); lev MODERATE LONG (held) | dealer 88.5th pctl, net +69,964 long VIX = low protection demand; AM net -66,500 short vol at z -2.71, the board’s most negative AM reading; 28.1% of lev gross in spread structure |
| 16 | Natural Gas | MANAGED MONEY STEPPED TO MODERATE SHORT | -0.06 to +0.32 (Δ +0.38) | -0.28 to -1.43 (Δ -1.15) | Commercials NEUTRAL (held); Managed Money (lev) NEUTRAL to MODERATE SHORT | Managed Money net -132,799 short; Swap Dealers z +2.26 on +227,587; Commercials net -14,084 |
| 17 | WTI Crude | MANAGED MONEY BACK TO NEUTRAL | +0.83 to +0.88 (Δ +0.05) | +0.94 to -0.12 (Δ -1.06) | Commercials MODERATE LONG (held); Managed Money MODERATE LONG to NEUTRAL | WTI Commercials net +319,539 (unusually net long for a hedger book), 83.7th pctl; Managed Money net +79,592; small traders z +0.95; top-4 9.6% |
| 18 | EUR | FOURTH WEEK OF DEALER BUILD | +1.00 to +1.06 (Δ +0.06) | -0.94 to -1.33 (Δ -0.39) | dlr MODERATE LONG (held); lev MODERATE SHORT (held) | dealer net -212,166 (short euro, high end of its short range, not a long), WoW +8,786; lev net -39,265 short euro; AM +220,603 holds the euro long; OptZ=+2.14 |
| 19 | USD Index | QUIET, AM HOLDS THE DOLLAR LONG | -1.00 to -1.16 (Δ -0.16) | -0.10 to +0.44 (Δ +0.54) | dlr MODERATE SHORT (held); lev NEUTRAL (held) | dealer 20.2nd pctl, net -17,924 (short DXY); AM +18,007 long DXY (z +1.21); small traders z +1.24; top-4 69.6% |
| 20 | Gold | HEDGERS HIGH, QUIET | +1.06 to +1.26 (Δ +0.20) | -0.15 to -0.33 (Δ -0.18) | Commercials MODERATE LONG (held); Managed Money NEUTRAL (held) | Commercials 78.8th pctl, net -20,540 hedge; Managed Money net +124,418 long; Swap Dealers z -0.77 |
| 21 | Silver | QUIET | +0.91 to +1.13 (Δ +0.22) | -0.86 to -1.30 (Δ -0.44) | Commercials MODERATE LONG (held); Managed Money MODERATE SHORT (held) | Commercials net -16,512 hedge; Managed Money net +7,614, still long outright; Swap Dealers z +1.04; small traders 25.3% of OI |
| 22 | JPY | NEUTRAL BASE | -0.43 to -0.23 (Δ +0.20) | +1.20 to +0.63 (Δ -0.57) | dlr NEUTRAL (held); lev MODERATE LONG (held) | dealer net -86,702 (short yen), WoW +21,582; lev net -14,161 short yen; AM z +0.40 |
| 23 | AUD | NEUTRAL BASE | -0.42 to -0.14 (Δ +0.28) | +1.47 to +1.50 (Δ +0.03) | dlr NEUTRAL (held); lev MODERATE LONG (held) | dealer net -8,787, WoW +19,221; lev net +60,592 long AUD; AM z -1.44; top-4 73.5% |
| 24 | Nasdaq (Consol) | QUIET | -0.12 to -0.09 (Δ +0.03) | +0.07 to +0.14 (Δ +0.07) | dlr NEUTRAL (held); lev NEUTRAL (held) | dealer 53.8th pctl, net -53,993; AM z +0.14; OptZ=-1.60; Mini dlr -0.09 to -0.09 (Δ +0.00) |
POSITIONING DYNAMICS
Rates (UST 2Y, UST 5Y, UST 10Y, UST 30Y, SOFR 3M)
Read as one curve, the dealer stress concentrated rather than rotated. Last week the dealer extreme sat only in the belly; this week the 2Y and 10Y joined it, so dealers are pinned at the bottom of their range across the whole 2Y-to-10Y span while both wings eased. The 10Y step is the week’s most unusual dealer short build: it came with no calendar catalyst, against a leveraged cohort that is neutral, so the counterparty to the dealer short there is the asset manager duration long, not a leveraged crowd. That combination (asset managers long futures, dealers short, leveraged funds short outright across the curve) is the footprint the options caveat describes: consistent with basis and directional hedging rather than options market-making.
The leveraged cohort tells a split story. In the 2Y the leveraged crowd kept extending against the dealer extreme, the one tenor where both sides are opposed at full stretch and still building, the configuration that would imply squeeze fuel if either side is forced to move. In the 5Y and 30Y the crowd released a tier, and at the long end dealers covered enough to reset to neutral. All leveraged books on the note complex remain short in absolute contract terms, so the z describes posture versus history, not an outright long. At the front end SOFR dealers released a tier but remain opposed to an elevated leveraged short; the SOFR options caveat and its heavy spread share mean the directional read overstates conviction.
Standing caveats, unchanged in substance: the options-implied dealer delta does not support the options-hedging hypothesis anywhere on the curve this week, now including the 5Y, and the measured realized-vol tilt is modest at the 2Y and 5Y and absent at the 10Y, so the short-gamma vol amplification inference stays a hypothesis.
FX (USD Index, EUR, JPY, GBP, AUD, CAD, CHF, MXN)
Sterling is the FX book that cleared the gate on level, flow and options at once. Dealers built a genuine long into the upper part of their range while the leveraged z fell to its range floor, but leveraged funds are still marginally long outright, so dealers and leveraged funds sit on the same side of the contract and the sterling short belongs to asset managers. The “opposed extremes” label is a z-score tension between two long books, not a long-versus-short standoff. The options-implied dealer delta is stretched long alongside the futures, the only stretched market where the tool records options corroboration this week, so the one place the options-hedging hypothesis has support. Sterling’s five prior ELEVATED LONG DELTA episodes (2026-07-07, 2026-06-16, 2026-03-10, 2025-12-09, 2024-04-23) returned a median +1.68% over four weeks, 5 of 5 bullish, against an unconditional base rate of +0.03% median and 51% bullish across 885 weeks. Five episodes, three of them this year, are historical context rather than a signal, and the window is anchored to Tuesday, so three sessions have already elapsed.
The rest of the FX tape was a dealer reset. CAD and MXN dealers covered back to neutral on outsized flow; in CAD the dealer book is a genuine long against a leveraged short, so the reset narrows an opposition rather than ending one, while in MXN dealers stay short the peso against a leveraged long that held near the top of its range. The franc released its stretch on both sides, leaving a genuine dealer long against a leveraged short at moderate levels. In the euro, dealers built for a fourth straight week but remain short the contract on the same side as leveraged funds, with the euro long sitting with asset managers.
Cross-checked against the Dollar Index, the buy-side still does not tell one dollar story: asset managers hold the DXY long and the sterling short, consistent with each other, but also hold the euro long outright. That split is worth a second look, not a headline. JPY and AUD moved on a neutral base and sat quiet.
Equities (S&P 500, Nasdaq, Russell 2000)
Russell 2000 is the equity book that moved a tier: the leveraged short deepened into its range floor against a dealer book that is genuinely long outright, the crowded-short configuration that would imply squeeze fuel if the short is forced to cover. The tool reads the dealer trend as declining, so the opposition is standing rather than building on both sides. S&P 500 dealers extended a four-to-eight-week covering trend that keeps them less short than usual, though still short the contract in absolute terms; the options-implied dealer delta stays stretched short in both large-cap indexes, so the futures-side covering is not echoed in the options book. Nasdaq sat at the mean.
VIX, one line: dealers long VIX reads as low protection demand, and the asset manager vol short deepened further at the board’s deepest asset manager stretch, unchanged in character from last week.
Crypto (Bitcoin, Ether)
The two crypto books moved in opposite directions. Ether dealers liquidated their structural long back to the mean on outsized flow, while the Bitcoin dealer long slid to the bottom of its range on outsized flow of its own. Standing caveat: crypto dealers are structurally net long, so Bitcoin’s negative z means a thin long, not an outright short, and leveraged funds in both names remain short outright despite the Bitcoin “crowded long” divergence label, which reflects their z, not their sign. The tool reads Bitcoin’s stress as decoupled from equity positioning, so it is not a broad risk-off read. Bitcoin’s five prior MODERATE SHORT DELTA episodes (2026-08-04, 2024-02-13, 2023-10-24, 2023-07-03, 2023-06-20) returned a median +8.51% over four weeks, 3 of 5 bullish, against an unconditional base rate of +2.10% median and 57% bullish across 625 weeks; the median is lifted by two large episodes and 3 of 5 is close to the base rate, so this is context, not a signal.
Commodities (Gold, Silver, WTI Crude, Copper, Natural Gas)
Copper released last week’s opposed stretch on both sides: Commercials eased back to a moderate hedge and Managed Money stepped down a tier, so the hedger-versus-speculator gap remains wide but no longer at full stretch. Positioning state only. Copper’s prior MODERATE SHORT DELTA episodes returned a median +1.40% over four weeks, 3 of 4 resolved bullish, against an unconditional base rate of +0.79% median and 55% bullish across 885 weeks; four resolved episodes are context, not a signal.
The speculative crowd stepped back across energy: WTI Managed Money cut its long back to neutral while WTI Commercials held their unusually net long posture, and natural gas Managed Money moved a tier deeper into its short. The natural gas Swap Dealer book remains pinned near the top of its range, a standing oddity. Gold and silver sat quiet, hedgers moderately high versus their own ranges.
COST BASIS LEVELS
| Market | Dealer Basis (Low-High) | Current Price | Dlr Gap | Lev Basis (Low-High) | Lev Gap |
|---|---|---|---|---|---|
| S&P 500 (E-Mini) | 6,634.95 – 6,832.73 | 7,777.00 | above zone | 7,211.15 – 7,417.10 | above zone |
| Nasdaq (Consol) | 28,986.82 – 29,924.14 | 31,060.00 | above zone | 29,345.13 – 30,486.67 | above zone |
| Russell 2000 | 2,824.76 – 2,923.52 | 2,851.90 | inside zone | 2,848.21 – 2,944.93 | inside zone, near the low edge |
| VIX | 15.49 – 18.83 | 15.37 | just below zone | 14.30 – 16.03 | inside zone |
| Bitcoin | 76,619.80 – 83,215.46 | 84,175.00 | just above zone | 74,231.07 – 80,627.32 | above zone |
| Ether | 2,324.53 – 2,559.01 | 2,664.22 | above zone | 2,322.35 – 2,530.30 | above zone |
| USD Index | 99.70 – 101.12 | 101.89 | above zone | – | – |
| GBP | 1.33 – 1.34 | 1.33 | at the low edge | 1.33 – 1.35 | at the low edge |
| CHF | 1.23 – 1.25 | 1.22 | below zone | 1.24 – 1.25 | below zone |
| Gold | 4,168.40 – 4,382.55 | 4,172.80 | inside zone, at the low edge | 3,967.90 – 4,181.31 | inside zone, at the top edge |
| Silver | 57.96 – 63.93 | 60.80 | inside zone | 64.98 – 72.04 | below zone |
| Copper | 5.84 – 6.09 | 6.58 | above zone | 6.01 – 6.26 | above zone |
| WTI Crude | 78.15 – 91.95 | 91.42 | inside zone, near the top edge | 80.91 – 93.37 | inside zone |
| Natural Gas | 2.84 – 3.15 | 3.04 | inside zone | 2.85 – 3.09 | inside zone |
Rates are excluded from cost basis by construction: structural shorts that never cross zero make the estimate unreliable. Russell 2000, gold, silver, WTI and natural gas trade inside their dealer or Commercial zone, so those aggregate epoch positions sit near flat P&L; VIX and the franc sit below theirs, sterling at the low edge, and the large-cap equity, crypto, dollar and copper books above. This is a descriptive P&L fact about the aggregate book; tested in 2026, no covering response follows a basis crossing, so none of these are triggers.
BOTTOM LINE
Treat the 2Y-to-10Y span as the crowded part of the curve going into CPI: the dealer short is at its range floor across all three tenors, but the options book does not back it anywhere, so size it as a basis-flow footprint with only modest measured vol tilt rather than as a gamma trade, while the long end and SOFR have partly decompressed. Outside rates, sterling is the one stretched book where futures and options positioning line up, and it is a two-long-books story, not a squeeze configuration.
Data: CFTC COT Report 2026-09-29 | Prices as of 2026-10-02 | Analysis window: 104 weeks
Smart Money Pulse - '26 W40
Treasury Dealers Hit Bottom in Three Maturities at Once, and Then Yields Ran to a 2002 High
As of Tuesday, dealers in the 2-Year, 5-Year and 10-Year Treasury all sat at the very bottom of their two-year ranges. Last week only the 5-Year was there; this week the 2-Year and the 10-Year stepped down to join it, and the 10-Year got there on the most unusual one-week dealer short build on the board.
The interesting part for your account is who holds the other side. In the 10-Year it is mostly the big asset managers, the pension and bond-fund money behind a core holding like BND, and they sit near the top of their own range. So this is less a hedge fund wager than a wide split between the institutions that run long-term savings and the desks that make markets for them.
This is Tuesday’s picture. Since then Treasuries sold off hard enough that headlines put yields at their highest since 2002 on Thursday, mortgage rates posted their biggest weekly jump in four years and a Fed official called for hikes of half a point or more. Yields came off their highs Friday after a cooler jobs report (nonfarm payrolls, the monthly count of jobs added), and stocks finished strong, with the Nasdaq up about one and a half percent since Tuesday. None of that shows how dealers handled the selloff; next week’s report is the first that can.
This Week’s Positioning
The 2-Year through 10-Year Treasury: the floor now runs the whole stretch
The 10-Year step was the sharpest of the three, an unusually large one-week build in the dealer short with no Fed meeting or options expiration nearby to explain it, and it leaves that book at the deepest dealer reading on the board (z=-2.75). In the 2-Year the hedge fund crowd sits at the opposite end of its own range and kept building toward it, though both groups are still short the contract outright, so the tension is about where each sits versus its history. Dealers’ options books are not stretched alongside them in any of the three maturities, which fits hedging and arbitrage trades better than a directional call on rates.
Watch: CPI (the consumer price index, the monthly inflation report) on October 14. It is the next scheduled number aimed squarely at these maturities, and you feel it through intermediate bond funds like BND and IEF.
The 30-Year Treasury: the long end let some air out
At the longest maturity it went the other way: dealers covered back to neutral on the largest weekly shift anywhere on the board, and the hedge fund crowd stepped down from the top of its range to a still-stretched reading (z=+1.51). Both groups remain short the contract outright, so this is tension draining rather than anyone switching sides. Long-dated funds like TLT took the brunt of the post-Tuesday selloff, but that is price action, not proof that anyone repositioned.
Watch: next week’s report, which shows whether the long-end crowd kept trimming through Thursday’s selloff or used it to add back.
Small caps: the fast money pressed its short to the edge
In the Russell 2000 the hedge fund crowd pushed its short down to the bottom of its two-year range (z=-2.03), now an extreme reading, and it has been adding for weeks. Dealers are on the other side with a genuine net long, which makes this the most one-sided bet against any stock index on the board; that describes a crowded arrangement, not a forecast either way.
Watch: the 2,825 to 2,945 band on the Russell 2000, which brackets where both groups built their positions and where the index sits right now. IWM is how most accounts hold this index.
The British pound: two long books and a short held by the big institutions
Dealers moved into the stretched upper part of their range with a genuine long on the pound (z=+1.75), and their options book is stretched the same way, the only market this week where the two line up. The hedge fund crowd’s position fell to the bottom of its own range but is still a hair long outright, so the bet against the pound belongs to the big asset managers rather than the fast money. For a U.S. investor this matters mostly through the dollar, which firmed about half a percent since Tuesday.
Watch: the pound near $1.33, the bottom edge of the zone where dealers built their long, which is where it ended the week.
Elsewhere: SOFR futures (the market’s bet on short-term interest rates) eased off their extreme but remain the contract where dealers and the hedge fund crowd are stretched in opposite directions. The Canadian dollar and Mexican peso dealer books reset to neutral on unusually large covering, and the Swiss franc released its stretch on both sides. Bitcoin’s dealer long, which is structural, slid to the thin end of its range on an outsized weekly move, a crypto-specific story with nothing similar in stock positioning. S&P 500 dealers kept covering for another week and are less short than usual, though still short outright, while the Nasdaq sits in the middle of its range. Institutions deepened their bet against volatility, the most stretched asset manager reading on the board, with the fear gauge near 15.4. In commodities, copper’s hedgers and speculative crowd both backed off a tier, the speculative crowd in crude oil cut its long back to neutral while the one in natural gas leaned further short, and gold and silver were quiet.
Know Where You Stand
- The quarter just turned, so find out whether your account is about to rebalance on autopilot. Many target-date funds, robo-advisers and 401(k) rebalancing features reset early in a quarter, and after a week when bond funds like BND fell while SPY rose, know which direction your mix is being nudged and that CPI on October 14 lands on the most crowded part of the bond market.
- Portfolio insurance is cheap right now, and that is worth knowing whether or not you buy any. With the VIX near 15 and institutions holding a historically rare bet against volatility, the cost of hedging an SPY or QQQ position, or of simply parking more in cash, is set off a calm market; this says nothing about whether calm lasts, only what protection costs today.
- Check whether your international fund hedges its currency exposure. The dollar index ended the week near 101.9 after firming since Tuesday, and an unhedged fund like VXUS gives up part of its return when the dollar rises while a currency-hedged fund does not, so look up which kind you own before the next swing decides it for you.
Data: CFTC COT Report 2026-09-29 | Prices as of 2026-10-02 | 104-week lookback

